Haynesville linked gas hubs have mostly traded sideways recently, with forward prices moving slightly lower amid strong gas production and a slow startup of Golden Pass LNG. Demand growth in Louisiana is expected to continue, resulting in the need for additional supply from the Haynesville. There appears to be ample pipeline capacity between northern and southern Louisiana over the next few years, supporting basis prices .
Discover the latest Columbia Gulf Mainline basis shifts, upcoming pipeline expansions like LEG and NG3, and the impact of rising LNG demand near Gillis on basis through 2026. Get continuous updates and actionable insights with our regularly updated Haynesville report.
Commentary
November 6, 2026 - Prompt month prices for NGPL TXOK and CGM moved in opposite directions again this week, with NGPL TXOK edging up 1c to -$0.47/MMBtu while CGM slipped 2c to -$0.33/MMBtu. The firmer TXOK prompt came as supply in the region dropped sharply, while TXOK winter prices weakened 3 to 5c. Downstream, TETCO ELA fell 7c in the prompt and WLA slipped 1c, tightening the prompt spread between Haynesville and southern Louisiana by about 2c. Eastbound flows out of Louisiana rebounded by about 0.8 Bcf/d as colder weather lifted Southeast demand, while LNG demand from Haynesville-fed terminals held steady, with Golden Pass running near full Train 1 rates. Dry gas production fell nearly 0.9 Bcf/d on the week to around 14.6 Bcf/d.
October 16, 2026 - Prompt month prices for NGPL TXOK and CGM moved in opposite directions this week, with NGPL TXOK falling another 4c to -$0.55/MMBtu, its weakest level since mid-June, while CGM moved up 1c to -$0.36/MMBtu. TXOK weakness was concentrated in November and December, with January through March little changed. Downstream, TETCO WLA was flat while ELA slipped 3c, potentially as eastbound flows out of Louisiana fell to a recent low near 7.0 Bcf/d and SONAT’s White Castle station ran constrained. The prompt spread between Haynesville and southern Louisiana widened for a second straight week, by about 4c. LNG demand held firm, with Sabine Pass and Cameron printing new highs and Golden Pass holding above 0.6 Bcf/d on most days. Supply slipped slightly this week, with dry gas production near 15.3 Bcf/d.
October 9, 2026 - Prompt month prices for NGPL TXOK and CGM weakened this week, with NGPL TXOK giving back last week’s gains, falling 6c to -$0.51/MMBtu, and CGM slipping 2c to -$0.37/MMBtu. TXOK winter prices were also off roughly 3c. Downstream, TETCO WLA held steady while ELA fell 4c, and the prompt spread between Haynesville and southern Louisiana widened back out by roughly 7c. The weakness came as Hurricane Isaias threatened Southeast demand, with eastbound flows out of Louisiana already falling by week’s end. LNG demand from Haynesville-fed terminals held firm, with Sabine Pass near recent highs and Golden Pass reaching a new high near 0.6 Bcf/d. Supply dipped early in the week on a brief drop in Haynesville receipts before recovering, with dry gas production near 15.4 Bcf/d.
October 2, 2026 - November NGPL TXOK reversed much of last week's selloff, rising 7c to -$0.45/MMBtu, while CGM slipped 3c to -$0.35/MMBtu. TXOK firmed down the curve as well, with winter prices up about 3c. The rebound came even as NGPL declared force majeure at CS 302, restricting eastbound flows out of East Texas into Louisiana. LNG feedgas demand was little changed at around 18.8 Bcf/d, with Golden Pass commissioning volumes still choppy. Downstream, TETCO WLA and ELA each firmed 1-2c, and the prompt spread between Haynesville and southern Louisiana tightened by about 5c. Supply was largely unchanged, with dry gas production near 15.5 Bcf/d.
September 25, 2026 - Prompt month prices diverged sharply this week. NGPL TXOK sold off, dropping 9c to -$0.48/MMBtu, while CGM slipped just 2c to -$0.35/MMBtu. TXOK traded lower down the entire curve, with winter off roughly 4c, while CGM forwards were little changed. Downstream, TETCO WLA firmed in the front and ELA weakened. The prompt spread between Haynesville and southern Louisiana widened, with TXOK cheapening more than 11c against WLA. Supply held near its highs, with dry gas production around 15.5 Bcf/d.
September 18, 2026 – Prompt month prices for NGPL TXOK and CGM pulled back this week, giving back some of the prior two weeks' gains. NGPL TXOK fell 3c to -$0.39/MMBtu and CGM slipped 2c to -$0.33/MMBtu. The move tracked a softer week for LNG feedgas demand, which eased to around 19.2 Bcf/d as Cameron flows sagged and Freeport took a one-day dip. Winter prices were little changed on both curves. Downstream, TETCO ELA actually firmed a few cents at the front while WLA held roughly flat, so the prompt spread between Haynesville and southern Louisiana widened back out, reversing the recent tightening. Supply eased slightly off its highs to 15.4 Bcf/d. On Friday, an explosion on TGT was reported, but it should have minimal impacts on regional pricing and the event appears to be contained.
September 11, 2026 - Prompt month prices for NGPL TXOK and CGM firmed again this week, with NGPL TXOK rising 4c to -$0.36/MMBtu and CGM up 5c to -$0.31/MMBtu. The move came as LNG feedgas demand climbed to a new high of 19.8 Bcf/d, led by commissioning volumes at Golden Pass. Unlike last week, the firming extended down the TXOK curve, with winter prices rising roughly 3c, while CGM forwards were little changed. Winter prices at downstream points, TETCO WLA and ELA, were largely flat this week rather than weaker. The prompt spread between Haynesville and downstream southern Louisiana continued to tighten, potentially as a result of sustained LNG demand. Supply firmed modestly to a fresh high near 15.7 Bcf/d.
Haynesville Basis Outlook and Notes
Summer 2026
All eyes will be on what Haynesville supply is able to do by middle of 2026. There are doubts that production will be enough to meet the LNG demand. If this is true, Henry Hub prices will rise as there would be an imbalance between demand growth from LNG and what the Haynesville would be able to provide.
This could mean that in order to get producers in the region to grow enough, Henry Hub gas prices need to rise further. Even if the Haynesville grows, new pipes that will enter service in late 2025 should provide ample egress capacity for some time.
Winter 2026-2027
LNG feedgas demand should be pushing towards record highs of more than 22 Bcf/d by the start of winter, resulting in a call on supply from the Haynesville. Gas supply out of the Permian will be rising at the same time due to the startup of the Blackcomb pipeline, but it may take some time for the pipe to fill, with any additional supply needed having to come from the Haynesville.
As public operators have continued to guide for flat production through the end of 2026, higher prices may be required to support the needed increase in gas supply.
Summer 2027
Demand growth will continue in 2027, as Venture Global's CP2 LNG export project and Train 1 of Sempra's Port Arthur terminal begin taking gas late in the year. LNG demand growth is mostly expected around the end of Summer '27.
2027 is expected to be a bigger year for power demand growth, with electricity demand rising sharply, potentially resulting in higher gas power burn.
For more discussion on basis price moves and the current forward curves:
For more discussion and charts, jump to our outlook and chart pack. Remember, the local market is influenced by the broader gas market. Consult our Gas Macro Outlook (note hyperlink to another article) for more.
Recent Market-Relevant Events
3.16.2026
Venture Global launches CP2 expansion
3.30.2026
Entergy to build 5.2 GW of gas generation for data center
4.08.2026
Commonwealth LNG set to reach FID in coming weeks
Infrastructure Outlook
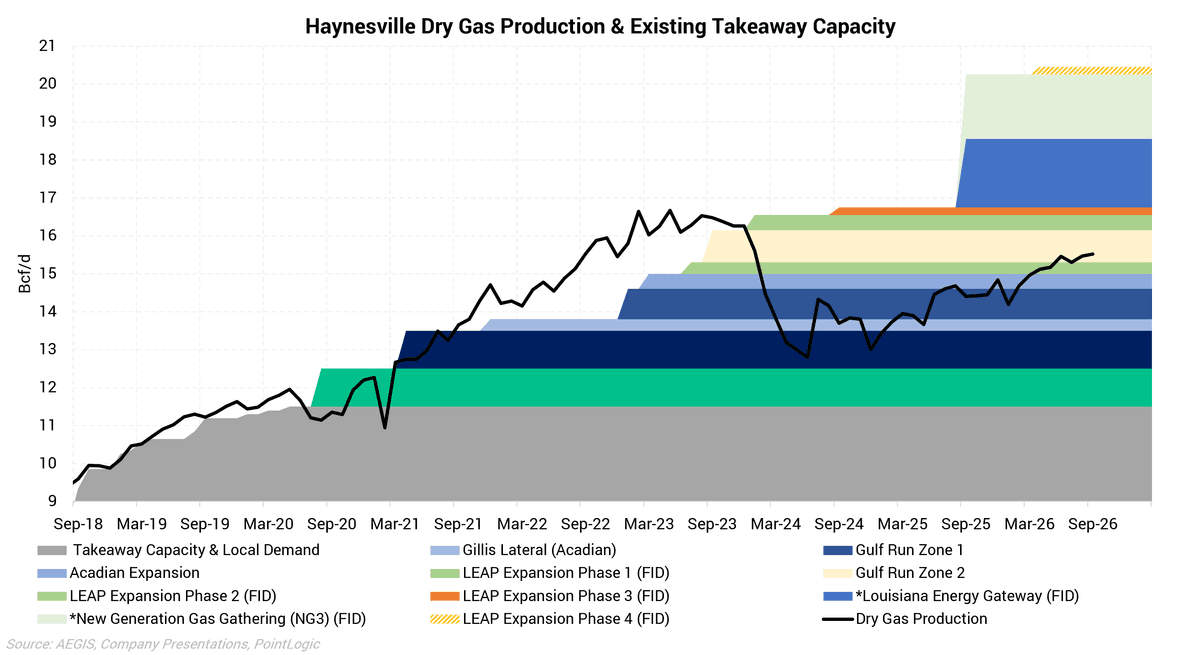
There is currently ample pipeline space available from the Haynesville into Southern Louisiana, due to the buildout in recent years and drop in production in 2024. Infrastructure and pipeline development will continue as supply grows sharply and more LNG export facilities are built. There are not expected to be any major constraints to getting gas out of the production area in the near-term.
For a discussion of production outlook:
Below are the most market-relevant infrastructure projects that appear to be funded and going forward. The projects that offer intra-region capacity (egress) are also shown in the chart above.
Note: Deeper discussion included below the map.


Gas Pipeline Projects
Pelican Pipeline
In-service date: H1 2027
Capacity: 1.7 Bcf/d
Source: WhiteWater
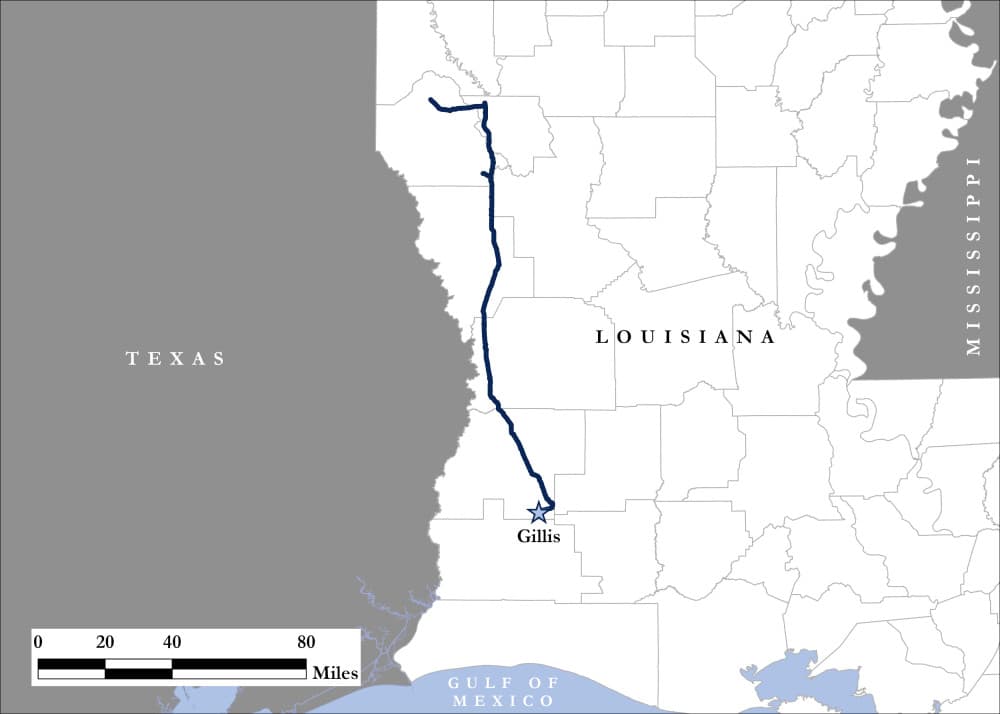
Pelican Pipeline - The WhiteWater Pelican Pipeline will transport up to 1.75 Bcf/d through approximately 170 miles of 36-inch pipeline from Williams, Louisiana, to the Gillis Hub near Ragley, Louisiana. Expected to be operational in the first half of 2027, the pipeline project is currently pending necessary regulatory approvals.
Other Projects
Blackfin Pipeline - The WhiteWater Blackfin Pipeline is a 193-mile, 42-inch intrastate natural gas pipeline that will deliver up to 3.5 Bcf/d from the Houston Ship Channel to Jasper County in East Texas. From there, it will interconnect with Venture Global’s CP Express Pipeline, delivering feedgas to the CP2 LNG terminal in Cameron Parish, Louisiana. With CP2 expected to eventually draw more than 4 Bcf/d of gas, Blackfin will serve as a critical Permian-to-LNG corridor. Construction is underway, and the pipeline is expected to enter service in the third quarter of 2025.
NGPL TX-LA Expansion Project - The project will increase NGPL's capacity by approximately 0.3 Bcf/d. The project will primarily involve additional compression to increase natural gas deliveries from existing system receipts, the growing Haynesville and South Texas supply to growing LNG markets. The project is targeted to be in service by July 1, 2026.
Trident Pipeline - Kinder Morgan’s Trident Pipeline is a 216-mile, 2.0 Bcf/d intrastate system moving Permian gas from Katy, Texas, to the Port Arthur LNG corridor near the Louisiana border. By targeting demand from Gulf Coast export terminals like Golden Pass LNG, Trident introduces direct competition to Haynesville producers supplying the same markets. Trident is expected to enter service in early 2027, with capacity expandable to 2.8 Bcf/d.
Local Supply
Recently gas production increased almost to a new record high of about 15.5 Bcf/d.
Supply in the Haynesville should grow sharply over the next few years, with the region needed to serve the vast majority of new LNG export demand. Gas output fell during 2024 as a weak price environment forced producers to curtail production and reduce activity. Output has essentially been flat but drilling activity has picked up sharply. According to Baker Hughes, gas directed drilling rigs operating in the Haynesville reached a multi-year high of 58.
Production
Operator Guidance
Comstock Resources (Q2 2026 EC)
07/30/2026
2026 Guidance
Q2 2026 Haynesville production of 113.1 Bcfe, roughly 1.24 Bcfe/d, up 16% sequentially
Management guides the Q4 2026 exit rate back to early-2024 peak levels, with Q3 and Q4 growing by similar sequential steps
Strategic & Infrastructure Highlights
Sold a 27% stake in Pinnacle Gas Services, its Haynesville gathering subsidiary, retaining 73% and rising to 80.5% after return hurdles
Haynesville sales points run roughly 50% Perryville and 50% WLA/NYMEX-linked, framing the basin's Gulf Coast basis exposure
Management continues to position Western Haynesville acreage to serve in-basin gas-fired power demand
Drilling & Basin Activity
2026 plan of 48 Legacy Haynesville wells drilled and turned to sales on 5 rigs
2026 plan of 22 Western Haynesville wells drilled and 21 turned to sales on 4 rigs, for 9 rigs basin-wide
Year-to-date Western Haynesville: 11 wells to sales averaging 31 MMcf/d initial production
Year-to-date Legacy Haynesville: 22 wells to sales averaging 31 MMcf/d initial production, including 8 horseshoe wells
Hedging Activity
63% of 2026 gas volumes hedged, down from roughly 75% a quarter earlier
780 MMcf/d hedged for 2026 through swaps and collars at $3.50 / $4.35
400 MMcf/d hedged for 2027 through collars at $3.50 / $4.44
Analyst Q& Takeaways
Western Haynesville remains the core long-term thesis, with the first 10,000-psi rig deploying in October 2026
A 20,000-lb frac spread is under discussion with an industry partner, targeted for 2027
Q2 pre-hedge realizations of $2.54–2.55 per Mcf reflected roughly a $0.35 discount to the $2.89 NYMEX average
Expand Energy (Q2 2026 EC)
07/29/2026
2026 Guidance
Q2 2026 Haynesville production averaged 3,187 MMcf/d, Expand's largest producing area, at a $2.62 per Mcf realized price
Full-year 2026 Haynesville guided to roughly 3,160 MMcfe/d — essentially flat to Q2, a managed rather than growth profile
Roughly 10 fewer Haynesville turn-in-lines are now expected this year, pushed into 2027
Strategic & Infrastructure Highlights
Q2 basis deduct to NYMEX in the Haynesville was $(0.28) per Mcf, the tightest of Expand's three operating areas
Delfin FLNG: 20-year, 1.15 MTPA FOB offtake agreement, FID reached June 2026, in service anticipated 2031
LNG view raised to 5.5–6 Bcf/d of new structural demand by the second half of 2027 and 19–24 Bcf/d incremental by decade-end
Twin Eagle adds 44 Bcf of storage and 9 Bcf/d of firm-transport-linked marketing reach into premium hubs
Management said takeaway is not currently a binding constraint on Haynesville volumes
Drilling & Basin Activity
Management expects 0.5–1.0 Bcf/d of additional Haynesville-wide growth in the second half of 2026, dependent on one operator's actions
Larger enhanced-completion fracs are lengthening pump and drill-out cycle times, deferring turn-in-lines
Added roughly 33,000 net acres in the Natchitoches Parish NFZ extension, adding 100-plus locations
Western Haynesville: second delineation well completed in Q2, first well on production, third planned later in 2026
Expand controls 75% of Tier 1 Haynesville inventory — over 2,000 locations, roughly 20 years
Hedging Activity
66% of 2026 gas production hedged and 41% of 2027 hedged, company-wide
Analysts Q&A Takeaways
Broader gas market seen modestly oversupplied through at least the first half of 2027 given roughly 3.5 Bcf/d of incoming Permian egress
Continued Haynesville growth optionality rests on unconstrained infrastructure access
Western Haynesville framed as an option rather than a requirement, given existing Tier 1 inventory depth
LNG demand growth described as landing "right in our backyard in Haynesville and Appalachia"
Rig Count
Local Demand
While gas consumption in Northern Louisiana, where most production is located, averages only 500 MMcf/d per month, the source of almost all US gas demand growth is directly to the south. LNG buildout in Southern Louisiana should drive growth in gas demand for the next few years. In addition, the Southeast region as a whole should see continued electricity demand growth, supporting gas-fired power burns.
LNG
LNG feedgas demand recovered this week as some facilities concluded maintenance events. Golden Pass LNG flows moved higher, nearing a record, but still not at Train 1 full capacity of 790 MMcf/d.
LNG feedgas will drive demand growth in Southern Louisiana going forward, and has already led to significant changes in gas flows and pricing. The majority of constructed and planned LNG export plants are situated near the border of Texas and Louisiana, in close proximity to Haynesville supply. Venture Global's Plaquemines LNG is the latest facility to enter service, with the plant ramping up to its full capacity over the next several months. Feedgas flows into the four currently operating Louisiana export plants can be seen in the charts below, in addition to the planned facilities.
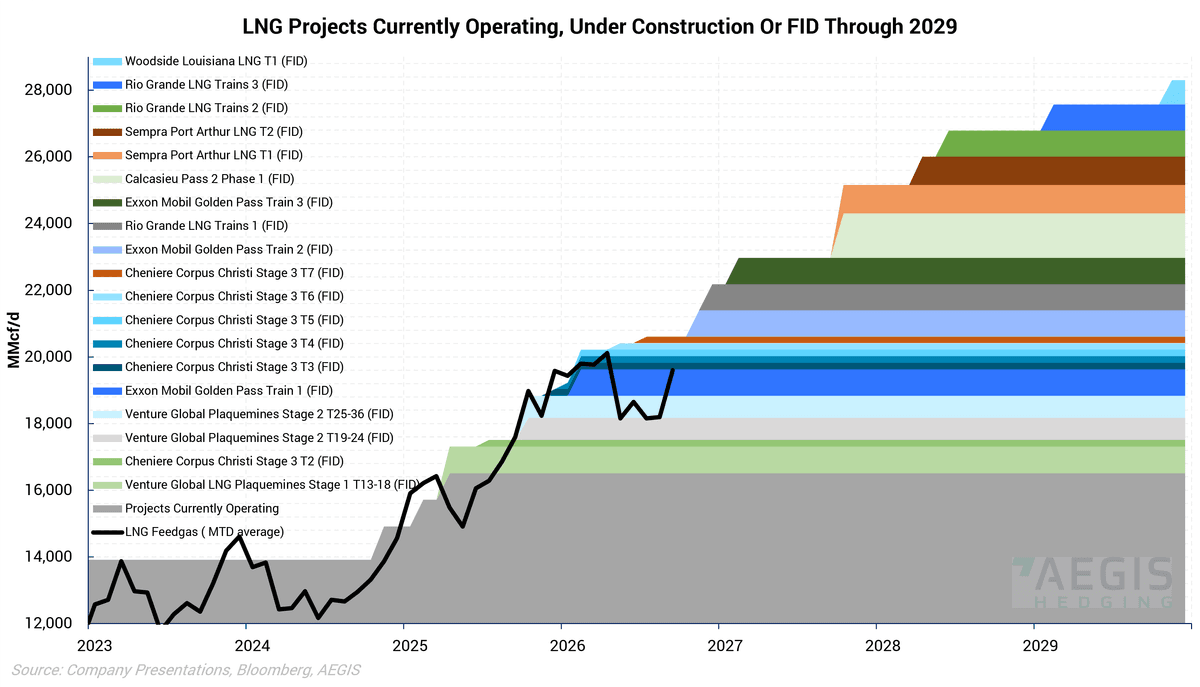
Chart Packet
Recent Market-Relevant Events
Commonwealth LNG to reach FID in coming weeks
(April 8, 2026)
Market Impact: After secruing a final investment decision, devleopers may move ahead with construction of the planned 1.2 Bcf/d Commonwealth LNG export terminal
- Several offtakers have already signed agreements to purchase supply from the plant, supporting project financing
- Operations are expected to begin in 2030
- Early site work has already begun, and orders for long-lead-time equipment have already been placed
Entergy to build 5.2 GW of gas power generation for data center
(March 30, 2026)
Market Impact: Rising power demand from data centers should support in-basin gas demand and Haynesville linked basis prices
- Entergy reached a deal with Meta to build seven new gas-fired power plants to support a Northeast Lousiana data center
- The new power plants will total 5.2 GW and builds on an earlier power supply deal with Meta
- Entergy has submitted a an application for the projects to the Louisiana Public Service Commission
Venture Global launches CP2 LNG expansion
(March 16, 2026)
Market Impact: Further expansions of Calcasieu Pass 2 will support LNG feedgas demand growth into the end of the decade
- While Calcasieu Pass 2 LNG is expected to begin taking gas in 2027, Venture Global is already preparing an expansion of the project
- The expansion will use a modular train system, like other Venture Global projects, resulting in a quicker installation and startup process
- The project is supported by a series of long-term offtake agreements signed without being linked to any specific Venture Global projects

Don’t stop here. See how other regions are performing right now:
Appalachian — Permian — Rockies — Midcon
Want this in your inbox?
AEGIS market analysts publish research across crude, natural gas, NGLs, refined products, metals, and rates.
Subscribe to research