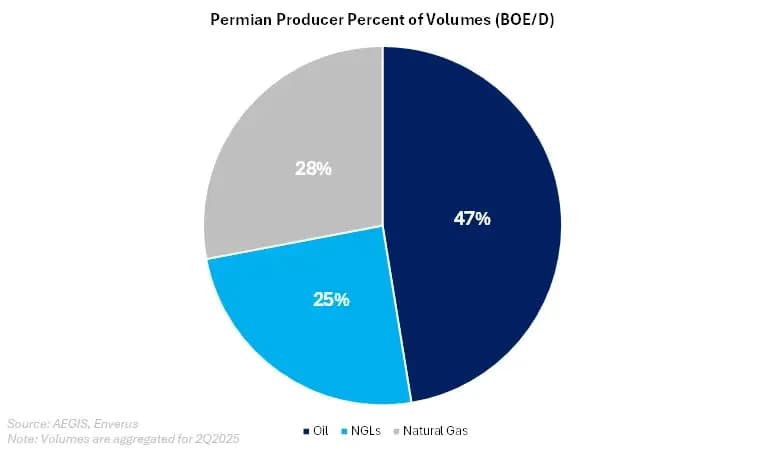
Natural gas liquids (NGLs) are distinct markets, but their prices inherit volatility from, and are influenced by, natural gas, crude oil, and petrochemical markets. However, each NGL product has its own unique supply-demand balance and inventory, both of which also cause price changes. Understanding the fundamental drivers and trading patterns of each NGL stream is essential for accurately evaluating the total revenue potential of oil and gas producers. Below, we explain how current events interact with microeconomic and trading principles for each NGL stream.
Natural gas liquids (NGLs) are distinct markets, but their prices inherit volatility from, and are influenced by, natural gas, crude oil, and petrochemical markets.
Special thanks to James Hawthorne, Texas A&M class of 2025, master's 2026 and TRIP Group 16. See his profile at LinkedIn.
Propane, butane, and natural gasoline have economic links to crude oil markets, so their prices are somewhat correlated to WTI. When there is a relative surplus of propane, for example, the ratio of propane's price to crude oil's price often decreases. However, if the price of crude oil is rising, propane prices could still rise. The chart below shows the progression of these NGL prices as a percentage of WTI price, on a barrel basis. Changes in these percentages often point to changes in supply, demand, exports, and inventory fundamentals. Propane and butane also have a seasonal pattern.
ethane
Ethane
In the last 10 years, ethane prices have been mostly determined by natural gas prices. Ethane has the flexibility to either be extracted and sold separately (at Mont Belvieu, TX or Conway, KS) or left within the natural gas stream (commonly called rejection). This flexibility creates a direct link between the two commodities.
Commentary
November 5: Ethane prices strengthened during October, averaging approximately $0.30/gal compared with $0.26/gal in September. With natural gas prices relatively stable, stronger exports and new cracker demand provided additional support to ethane and kept recovery economics favorable. The latest EIA data through August show production near 3.36 MMBbl/d and exports reaching a record 794 MBbl/d, reinforcing the importance of international demand in absorbing growing US supply.
October 7: Ethane prices averaged approximately $0.25/gal in September, up from $0.24/gal in August as stronger natural gas prices provided additional support. Henry Hub moved closer to $3/MMBtu as the storage surplus narrowed. Ethane continues to trade primarily on natural gas and rejection economics, leaving it less exposed than the heavier NGLs to the recent move in crude. The latest EIA data, which run through July, show production holding near 3.32 MMbbl/d. Inventories rose to roughly 74.1 MMBbl as exports eased to 674 MBbl/d from a record 770 MBbl/d in June, allowing more supply to remain in the domestic market
September 4: Ethane prices averaged approximately $0.24/gal in August, holding near June and July levels. US production eased from May’s record high to roughly 3.31 MMBbl/d in June, while inventories also slipped below 73 MMBbl. Export demand remains the key outlet for growing US supply, with June exports reaching a record 770 MBbl/d and surpassing the previous high set in March. Continued additions to the VLEC fleet should provide more capacity to move US ethane into international markets as production expands.
August 5: Ethane prices were little changed in July, averaging roughly $0.23/gal as Henry Hub prices remained near June levels. Ethane continues to trade primarily on natural gas and recovery economics, leaving it less exposed than the heavier NGLs to the renewed volatility in crude and global LPG markets. US production reached another record in May at approximately 3.44 MMBbl/d. Inventories held near 73 MMBbl as strong export demand helped absorb rising supply and slowed the typical seasonal stock build.
July 10: Ethane prices strengthened modestly through June, averaging roughly $0.23/gal as firmer natural gas prices improved recovery economics. Unlike the heavier NGLs, ethane remained largely insulated from the decline in crude oil prices following the easing of geopolitical tensions in the Middle East, with pricing continuing to track natural gas fundamentals.
Recent Market-Related Events
November 5: Energy Transfer is expanding its Marcus Hook terminal with approximately 900 MBbl of refrigerated ethane storage and 20 MBbl/d of additional chilling capacity. The project should provide additional flexibility for Northeast ethane exports, which primarily serve European markets.
October 7: The global ethane trade fleet remains at 51 VLECs. Thirteen new vessels have been delivered in 2026, another six are expected before year-end and 27 are scheduled for delivery in 2027.
September 4: Enterprise’s Neches River Phase 2 terminal is expected to remain primarily focused on propane through 2026 before shifting toward ethane in 2027. The flexible train can load up to 180 MBbl/d of ethane or 360 MBbl/d of propane.
July 10: Energy Transfer announced an expansion of its Nederland export terminal that will add approximately 240 MBbl/d of ethane export capacity and 55 MBbl/d of additional LPG export capacity. The project is expected to enter service in phases beginning in 2028 and should further strengthen the long-term outlook for US ethane exports.
June 23: Analysts expect 11.8 Mt/year of new global ethylene capacity through 3Q26. However, much of the capacity is expected to rely on naphtha, mixed-feed, or refinery-integrated configurations rather than pure ethane cracking. The largest direct driver of US ethane demand is the 2.1 Mt/year Golden Triangle Polymers project, which could consume roughly 110 MBbl/d of ethane.
Ethane Background
Ethane Rejection Economics:
- Ethane can be "rejected," meaning producers (or the operator of a processing plant) leave ethane in the natural gas stream instead of recovering it, usually when ethane's market value is low relative to that of natural gas.
- When natural gas prices rise relative to ethane, producers prefer ethane rejection, reducing ethane supply and supporting ethane prices. Conversely, lower natural gas prices encourage ethane extraction, increasing supply and pressuring ethane prices downward. This relationship means that if the price ratio between ethane and local natural gas becomes too small or too large, ethane rejection can correct the imbalance.
Extraction Flexibility:
- Ethane recovery is economically viable when the price spread (the "frac spread") between ethane and natural gas is favorable.
- Producers regularly monitor this frac spread. If natural gas prices climb significantly, the relative incentive to extract ethane diminishes, reducing ethane supply and aligning ethane price movements with natural gas trends.
Infrastructure and Market Linkages:
- Many natural gas processing facilities have the option to easily switch between ethane recovery and rejection based on economics.
- This operational flexibility means ethane supply frequently responds to shifts in natural gas pricing, tightening the correlation between their prices.
Market Demand and Export Dynamics:
- US ethane demand heavily depends on petrochemical cracking and export markets. However, these demand factors often adjust slowly compared to changes in natural gas economics, leaving natural gas price dynamics as the primary short-term driver of ethane price direction.
Fundamentals
Ethane production continues to trend higher, reaching a record highs in recent months. Growth remains driven by strong associated-gas output in oil basins, especially the Permian, where wide gas discounts support high recovery rates. Nearly all US ethane is extracted at gas processing plants, and recovery has stayed elevated as NGL-rich gas streams continue to expand.
Note: The EIA does not include rejected ethane in its field production numbers. Rejected volumes are captured in natural gas production.
US exports are expected to benefit from a rapidly expanding Very Large Ethane Carrier fleet and are expected to absorb part of the seasonal supply growth and may limit the pace of inventory builds through the summer. The larger fleet should provide the shipping capacity needed to support continued growth in US ethane exports.
There are new ethane export terminals that will increase exports of ethane.
US ethane demand continues to run firm, based on the latest EIA data. Ethane remains the most cost-advantaged feedstock for US steam crackers, and utilization rates have been healthy enough to keep domestic pull consistently strong.
US ethane production has trended higher alongside growth in associated gas production and strong recovery economics. Because domestic petrochemical demand changes relatively slowly, exports have become an increasingly important outlet for incremental supply. Strong export demand can help absorb production growth and limit inventory builds, while weaker exports or stronger recovery can leave more ethane in the domestic market and put upward pressure on inventories.
Ethane supply also has more flexibility than the heavier NGLs because processors can adjust recovery rates when the value of ethane changes relative to natural gas.
propane
Propane
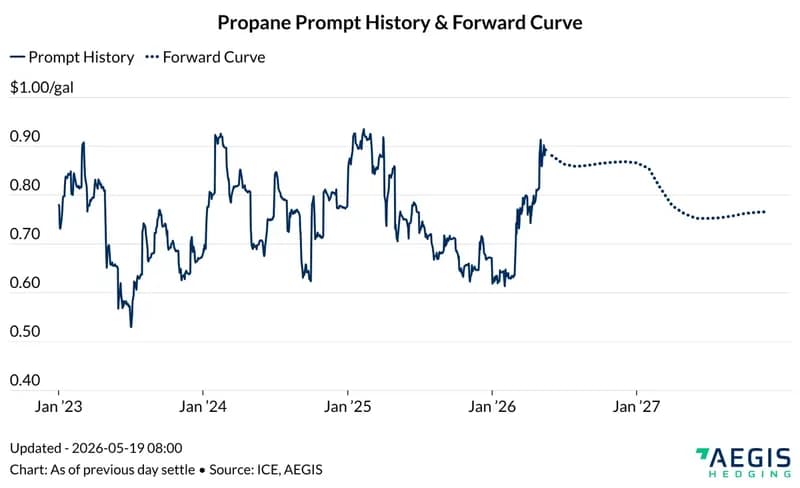
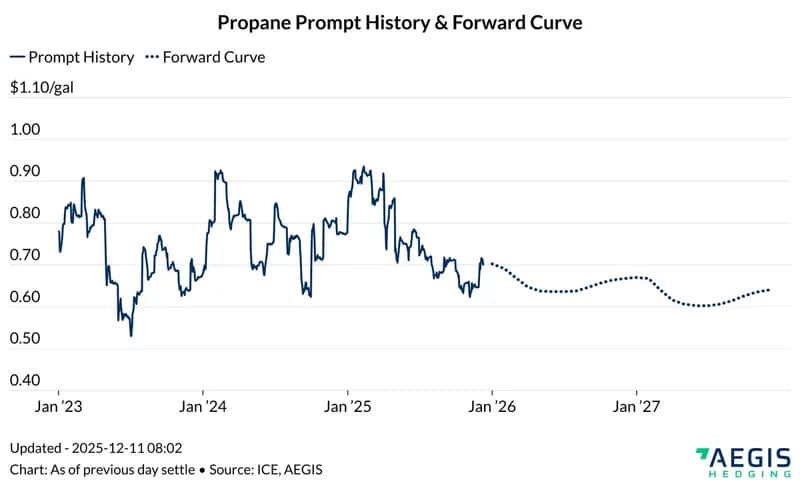
Propane prices in the US are influenced by crude oil prices, other NGL prices, weather, and propane's own supply, demand, and inventory balance. Unlike ethane, propane cannot be rejected into the natural gas stream in large amounts. Propane's relative value to oil typically strengthens when domestic inventories are low (that is, demand has been relatively high compared to supply) and weakens when the US propane market is well-supplied. Because of this interaction between propane's economics and other market prices, propane's price history is complex.
Commentary
November 5: Propane rallied sharply during October, averaging approximately $1.04/gal compared with $0.82/gal in September, while the propane-to-WTI ratio climbed to roughly 45%. Strong exports, firmer Asian pricing and rising seasonal domestic demand have begun tightening a market that entered fall with elevated inventories. Although national stocks remain comfortable, inventories are increasingly concentrated along the Gulf Coast to support exports, leaving consuming regions more exposed to localized tightness if winter demand surprises to the upside.
October 7: Propane prices rebounded during September, averaging approximately $0.81/gal compared with $0.69/gal in August, while the propane-to-WTI ratio rose to roughly 37% from 35%. Despite the rally, domestic fundamentals remain well supplied heading into the heating season. The latest monthly EIA data through July show production near 2.42 MMBbl/d and exports near 1.91 MMBbl/d, while more timely weekly inventory data continue to show stocks well above seasonal norms. Strong winter exports could help work down the surplus, but a warmer-than-normal weather outlook limits the risk of a sstained price spike.
September 4: Propane prices weakened further during August, averaging approximately $0.68/gal compared with $0.71/gal in July. The propane-to-WTI ratio fell to roughly 36% from 37% as strong domestic supply and record inventories outweighed resilient export demand. US stocks reached approximately 110 MMBbl in mid-August, leaving the market with a sizable cushion heading into the winter heating season. Inventories remain above the five-year average, and additional export demand is unlikely to tighten the balance quickly enough to materially change the near-term outlook. A warmer-than-normal winter could further limit domestic heating demand and reduce the risk of a sustained winter price rally.
August 5: Propane prices continued to weaken in July, averaging approximately $0.71/gal compared with $0.75/gal in June. The propane-to-WTI ratio remained near 38%, indicating that propane broadly kept pace with movements in crude even as domestic fundamentals remained heavily supplied.
July 10: Propane prices weakened through June as crude oil prices retreated following the easing of supply concerns in the Middle East. Despite the decline in outright prices, propane strengthened relative to WTI as crude fell more sharply, lifting the propane-to-WTI ratio from roughly 35% in May to 39% in June. Domestic fundamentals remain well supplied, supported by robust associated-gas production and rising inventories, while export demand continues to provide an important outlet for excess supply. Looking ahead, increased LPG availability from the Arabian Gulf and narrower export arbitrage into Asia may limit additional upside for US propane prices even as Gulf Coast export capacity continues to expand.
Recent market-related events
October 7: Repauno's Phase 2 expansion is expected to add roughly 72 MBbl/d of East Coast propane/LPG export capacity in early 2027. The project will provide an additional outlet for growing Northeast supply and reduce reliance on Marcus Hook and Gulf Coast export terminals.
September 4: Enterprise’s Houston Ship Channel expansion is expected to add approximately 300 MBbl/d of LPG export capacity by the end of 2026. The additional outlet should help absorb growing US propane and butane supply, although the current propane inventory surplus suggests the market will remain well supplied heading into winter.
August 5: Enterprise’s Neches River Phase 2 terminal is expected to remain focused primarily on propane during the second half of 2026 before transitioning toward ethane service in 2027. The temporary propane capacity should provide an additional outlet while US inventories remain elevated.
July 10: Energy Transfer announced an expansion of its Nederland export terminal that will add approximately 55 MBbl/d of LPG export capacity alongside a larger ethane expansion. The project, expected to begin service in phases starting in 2028, should provide additional flexibility for US propane exports as domestic production continues to grow.
June 4: Export infrastructure remains a key focus for propane markets. Enterprise's Neches River Phase 2 facility has added incremental LPG loading flexibility along the Gulf Coast, while additional export projects are expected to come online through late 2026. Enterprise will complete a 300 MBbl/d LPG expansion at its Enterprise Houston Terminal by the end of 2026. Tyler Cott, SVP for Hydrocarbon Marketing, said ”We expect (Neches River Terminal) to do a good amount of propane in the balance of this year; that will transition to ethane as our (Enterprise Hydrocarbons Terminal) capacity comes online late this year.”
Propane Background
Reasons why propane prices follow crude oil prices:
Petrochemical Demand:
- Propane serves as a feedstock in petrochemical plants, particularly in propane dehydrogenation plants (PDH) and in steam crackers, which can switch feedstocks based on price competitiveness between propane and other feedstocks (usually ethane and butane in the US).
- Rising crude prices often lift naphtha prices, making propane a more attractive feedstock for petrochemical plants (globally) and thus supporting propane prices.
Heating Dynamics:
- Propane demand is seasonal, because it is a heating fuel in winter. Because of the concentration of demand in winter months, propane prices also follow the seasonal pattern of higher prices in winter and lower prices in summer.
- Propane is consumed from on-site tanks at end-user facilities (home, business, industrial location), rather than delivered directly from a pipeline. Therefore, demand statistics from the US EIA often appear after the fact, when the retail distribution network refills from primary storage at the fractionator sites.
Export and Global Pricing Influences:
- The US exports significant volumes of propane, linking domestic prices to international LPG (Liquefied Petroleum Gas) markets, which are heavily influenced by global crude benchmarks.
- When crude prices increase internationally, overseas propane benchmarks like the Saudi Aramco contract price typically rise, encouraging maximum exports from the US.
Infrastructure and Storage Dynamics:
- US propane storage and export infrastructure allows propane markets to rapidly respond to global crude-driven market signals.
- Robust export capacity connects domestic propane pricing closely to crude-driven global LPG demand.
Influence of Propane’s Own Supply-Demand Balance
- While propane pricing largely tracks crude oil, propane’s own domestic supply-demand fundamentals independently affect its relative pricing and market value.
- When US propane inventories are low, typically due to strong domestic or export demand, propane’s price premium relative to crude tends to increase.
- Conversely, if propane supply exceeds domestic and export demand, resulting in higher inventories, propane’s value relative to crude often weakens, even if crude prices remain stable or strong.
Fundamentals
Propane production comes from rich-gas plays and from associated gas in major oil basins. Output remains strong, supported by steady NGL recovery from the Permian and other shale regions. While propane supply continues to grow, the pace of increases has moderated compared with the rapid expansion seen between 2022 and 2024, reflecting slower growth in gas processing volumes.
US propane exports are a critical outlet for balancing growing domestic supply. With US production consistently exceeding domestic demand, access to international markets helps prevent excess barrels from accumulating in storage. Export economics depend on the spread between US and international propane prices, terminal costs and VLGC freight rates, while Asian demand remains an important source of incremental buying. Continued expansion of US export infrastructure should provide additional flexibility to move growing supply overseas when arbitrage economics support shipments.
Seasonal weather remains the largest driver of US propane demand, with heating needs causing wide swings during winter months. Chemical and agricultural uses provide a steady year-round baseline, and recent data shows domestic demand averaging above both 2024 levels and the five-year average.
Lower 48 propane inventories have remained above the five-year average in recent years, weighing on propane’s relative value versus crude. Elevated inventories continue to pressure the propane-to-WTI ratio, limiting upside even as crude prices strengthen. US propane inventories surpassed 100 MMBbl during July. Stocks do not typically reach that threshold until late September or early October, highlighting the extent of the current domestic supply surplus.
butane
Butane
Butane, specifically normal butane (n-butane), is a natural gas liquid (NGL) produced primarily during natural gas processing and petroleum refining. It's distinct from propane and ethane due to its heavier molecular structure and distinct market uses. Like propane, butane closely tracks crude oil due to its end-uses in transportation and petrochemicals.
Commentary
November 5: Normal butane rallied sharply during October, averaging approximately $1.75/gal compared with $1.28/gal in September, while its value relative to WTI increased to roughly 74% from 55%. The full transition to winter-grade gasoline increased refinery blending demand at the same time strong exports continued to pull barrels overseas. With inventories entering the blending season below the five-year average, continued export demand and winter blending should accelerate seasonal draws and keep the balance relatively tight.
October 7: Normal butane strengthened sharply during September, rising to approximately $1.27/gal from $1.05/gal in August. Its value relative to crude increased to roughly 55% of WTI from 53% as the market shifted into winter gasoline blending. Higher gasoline prices, stronger octane values and unusually low gasoline inventories improved blending economics and increased refinery demand for butane. The latest EIA data through July show inventories had still been building seasonally, rising to roughly 56.1 MMBbl, although stocks remained below both year-ago levels and the five-year July average. Exports eased to 693 MBbl/d from 818 MBbl/d in June after the record levels seen earlier in the spring.
September 4: Normal butane strengthened further relative to crude during August, with the butane-to-WTI ratio rising to approximately 54% from 53% in July. Mont Belvieu prices increased to roughly $1.04/gal from $1.00/gal as Middle East supply disruptions increased demand for replacement barrels outside the region and supported US pricing despite challenging export economics. The domestic balance has also tightened ahead of winter gasoline blending. Strong exports and elevated summer blending demand slowed the seasonal inventory build, while an earlier transition to winter-grade gasoline is bringing additional blending demand into the market sooner than usual.
August 5: Normal butane strengthened relative to crude during July, with its value rising to approximately 53% of WTI from 50% in June. Outright prices increased by only about $0.01/gal, but crude weakened more sharply, allowing butane to outperform on a relative basis. The butane-to-propane spread widened as Middle East supply and shipping disruptions increased demand for barrels sourced outside the region. The resulting record export activity has limited the seasonal build in normal butane inventories.
July 10: Normal butane prices weakened through June as export demand slowed following record shipments earlier in the spring. While lower crude oil prices weighed on the broader NGL complex, butane underperformed relative to propane as the butane-to-propane spread narrowed from May's elevated levels. Seasonal gasoline blending demand also continued to fade under summer Reid Vapor Pressure (RVP) specifications, reducing domestic consumption. Looking ahead, export demand will remain the primary source of support for butane prices, though softer Asian pricing and narrower export arbitrage may continue to pressure the market.
Recent market-related events
September 4: US butane exports set three consecutive monthly records, rising from 661 MBbl/d in March to 815 MBbl/d in April and 893 MBbl/d in May before easing to 818 MBbl/d in June. India has emerged as an important source of incremental demand as buyers look to the US for additional LPG supply. India’s warmer climate also allows LPG distributors to use a greater share of butane in propane-butane blends. Normal butane boils at roughly 31°F compared with about -44°F for propane, meaning warmer ambient temperatures allow butane to vaporize effectively while its lower vapor pressure makes it well suited for higher-butane LPG blends.
August 5: The EPA has continued to renew a nationwide fuel waiver allowing a common 10-psi gasoline pool through August 8. The waiver provides refiners with some additional blending flexibility, although summer vapor-pressure restrictions still sharply limit the amount of normal butane that can enter the gasoline pool.
Butane Background
US Butane Market Overview
Key Uses:
- Gasoline blending (primary, seasonal)
- Petrochemicals (producing isobutane, butadiene, alkylate)
- Heating fuel (minor, compared to propane)
- Exports (primarily Asia, Latin America, Europe)
Supply Sources
- Natural Gas Processing: Primary source, separating butane along with other NGLs (propane, ethane, pentanes).
- Refineries: Secondary source from crude oil processing.
Infrastructure & Storage
- Primarily stored in Gulf Coast salt dome caverns (Mont Belvieu, TX).
- Transported domestically via pipelines, rail, and trucks.
Domestic Demand
- Peak in winter (Oct-Mar): Increased use in gasoline blending due to higher allowable vapor pressure.
- Reduced in summer (Apr-Sep): Regulatory limits lower blending demand.
- Consistent year-round petrochemical demand.
Seasonal Pricing Patterns
- Winter: High blending demand elevates prices relative to crude oil, peaking around Jan-Feb.
- Summer: Reduced blending leads to excess supply, softening prices; excess typically exported or stored.
Exports
- Growing due to rising US production.
- Key markets: Asia (Japan, South Korea), Latin America, Europe.
Pricing Dynamics
- Quoted at major NGL hubs (primary benchmark: Mont Belvieu).
- Influenced by:
- Crude Oil Prices: Close correlation due to shared end-markets.
- Gasoline Market Dynamics: Competition with natural gasoline, ethanol, and refining margins.
- Natural Gas/NGL Production: Higher production can depress prices if demand lags.
- Export Conditions: Increased exports support domestic pricing.
- Inventory Levels: High inventories pressure prices; low inventories support pricing.
General Market Principles
- Butane pricing closely tracks crude oil due to similar applications.
- Seasonal inventory cycles: builds in summer/fall, draws in winter, monitored closely by the market.
- Mont Belvieu prices serve as key benchmarks for domestic and international contracts.
Fundamentals
Butane production comes from gas produced in rich-gas plays and associated gas from oil plays. Its growth rate is almost identical to that of propane. The chart to the right shows normal butane and isobutane production combined.
Most butane exported is normal butane, and it is exported mostly from facilities that can also export propane.
Butane demand is seasonal and is used domestically as a blending fuel in the winter to improve cold-weather starting. Chemical and Isomerization uses of butane are fairly steady year-round. It is the use of butane in refineries that experiences the most volatility.
Steady supply typically allows normal butane inventories to build during the summer as gasoline-blending demand declines. As refiners transition to winter-grade gasoline, looser vapor-pressure specifications allow greater butane blending, increasing seasonal demand and drawing inventories.
Isobutane
Isobutane
Isobutane is produced at gas processing plants, refineries and through isomerization units that convert normal butane into isobutane. Its value is closely tied to octane markets because it is primarily used as a feedstock for producing alkylate, a high-octane gasoline component. Demand is generally steadier than normal butane but still varies with gasoline seasonality, refinery utilization and octane economics. The market is relatively thin, so even modest shifts in refinery demand or supply can create sharp price moves. Isobutane typically trades at a premium to normal butane, although the spread can narrow when normal butane strengthens or demand for alkylation feedstock weakens.
Commentary
November 5: Isobutane prices surged during October, averaging approximately $1.89/gal compared with $1.39/gal in September. Strong octane values and favorable alkylation economics kept refinery demand firm even as seasonal support would normally begin to ease. The isobutane premium over normal butane widened modestly, while the market's relatively limited liquidity amplified the move.
October 7: Isobutane prices softened during September, averaging approximately $1.38/gal compared with $1.41/gal in August. The decline came despite stronger octane values as the early transition to winter-grade gasoline shifted refinery demand toward normal butane as a direct blendstock and away from incremental alkylate production. The latest EIA data through July show isobutane production increased to roughly 502 MBbl/d, underscoring continued supply growth heading into the seasonal shift in refinery demand. Normal butane consequently outperformed isobutane during September, compressing the isobutane premium after its strong summer rally.
September 4: Isobutane prices strengthened sharply during August, averaging approximately $1.43/gal compared with $1.12/gal in July. Strong alkylate margins increased refinery demand for isobutane as a feedstock, while elevated gasoline cracks and the value of high-octane blending components provided additional support. The isobutane premium over normal butane reached approximately $0.46/gal in mid-August before narrowing to roughly $0.26/gal late in the month. The pullback reflects the seasonal transition away from peak summer alkylation demand at the same time normal butane is beginning to receive more support from winter gasoline blending.
August 5: Isobutane fundamentals remain relatively well supplied, with steady refinery and alkylation demand continuing to offset strong production. US supply held near 480 MBbl/d in May, while inventories remained around 14.2 MMBbl and above the five-year average. The elevated inventory position should limit sustained price upside, although isobutane remains a relatively thin market and can respond sharply to refinery outages, changes in alkylation demand or stronger octane values.
July 10: Isobutane prices softened through June alongside the broader C4 complex as lower crude oil prices weighed on NGL values. Unlike normal butane, however, demand remained supported by relatively steady refinery and alkylation activity, helping limit downside despite ample supply growth. As refinery utilization remains healthy, isobutane pricing is expected to continue tracking gasoline blending economics and octane demand more closely than broader export markets.
Recent market-related events
Coming soon
Isobutane Background
US Isobutane Market Overview
Key Uses:
- Alkylation feedstock for producing high-octane gasoline components
- Petrochemical feedstock for specialty chemicals
- Refinery blending and octane enhancement
- Occasional exports, typically when domestic supply outpaces refinery demand
Supply Sources
- Natural Gas Processing: Baseline production of isobutane alongside other NGLs
- Refineries: Additional volumes produced through crude oil fractionation
- Isomerization Units: Convert normal butane into isobutane to meet refinery alkylation needs
Infrastructure & Storage
- Stored primarily in Gulf Coast salt dome caverns, often alongside other butane streams
- Moved by pipeline, rail, and truck to refineries and petrochemical plants
- Limited storage relative to propane and normal butane due to smaller market size
Domestic Demand
- Demand is steady year-round because alkylation units operate continuously
- Less seasonal than normal butane since its primary use is octane production, not vapor-pressure blending
- Sensitive to refinery utilization and octane economics
Pricing Dynamics
- Prices are quoted at major NGL hubs such as Mont Belvieu
- Influenced by:
- Octane values and gasoline-blend economics
- Normal butane prices, due to isomerization flexibility
- Crude oil trends as broader energy benchmarks
- Refinery runs and alkylation margins
- Typically trades at a premium to normal butane, with the spread narrowing when:
- Normal butane strengthens sharply, or
- Octane values soften
General Market Principles
- Isobutane is a thinner market, so prices can move quickly when refinery demand shifts
- The ability to convert normal butane into isobutane via isomerization helps balance supply
- Pricing tends to follow octane markets more closely than crude
- Inventory levels can fluctuate rapidly due to the smaller market size and refined-product linkages
nat
Natural Gasoline
Natural gasoline (C5+) is produced mainly at gas processing plants and closely tracks light crude and naphtha because it competes directly in gasoline blending and export markets. Demand is anchored by its role as a blendstock and as diluent for heavy crude, providing steady baseline pull. Prices typically follow WTI, and the natural-gasoline-to-crude ratio weakens when domestic supply outpaces blending or diluent needs.
Commentary
November 5: Natural gasoline strengthened sharply during October, averaging approximately $2.23/gal and rising to roughly 98% of WTI from 89% in September. Stronger Asian naphtha values increased the relative value of US natural gasoline as a substitute feedstock, while domestic gasoline-blending demand provided additional support. The latest EIA data through August show production near 1.0 MMBbl/d, underscoring continued supply growth even as international naphtha economics remain an important driver of the marginal barrel.
October 7: Natural gasoline strengthened in outright terms during September alongside crude but weakened on a relative basis, falling to approximately 89% of WTI from 92% in August. The move reflected weaker Asian naphtha relative to crude, reducing the relative value of natural gasoline as a substitute feedstock even as outright prices increased. The latest EIA data through July show US production rising to approximately 987 MBbl/d while inventories increased modestly to 25.3 MMBbl and exports held near 166 MBbl/d. Those figures point to continued growth in domestic supply, but September pricing was driven primarily by weaker naphtha values relative to crude.
September 4: Natural gasoline weakened modestly relative to crude during August, falling to approximately 93% of WTI from 95% in July. The move reflected weaker Asian naphtha values relative to crude, reversing part of the sharp relative strength seen in July. Natural gasoline remains tied to WTI, but the marginal US barrel increasingly clears through export markets as a substitute for naphtha. As a result, changes in the naphtha-to-crude relationship can have a larger impact on natural gasoline’s relative value than crude prices alone.
August 5: Natural gasoline strengthened sharply relative to crude during July, rising to approximately 95% of WTI from 84% in June. The move was driven largely by stronger Asian naphtha prices, which increased the value of US natural gasoline as a substitute feedstock. With Asian naphtha rising faster than crude during the month, natural gasoline strengthened relative to WTI.
July 10: Natural gasoline prices weakened through June as crude oil and Asian naphtha markets retreated following the easing of supply concerns in the Middle East. On a percentage-of-WTI basis, natural gasoline declined from roughly 90% in May to 84% in June as softer international naphtha values reduced export netbacks. While domestic production continues to increase alongside broader NGL supply growth, pricing remains driven primarily by global crude and naphtha markets rather than US supply-demand fundamentals.
Recent market-related events
Coming soon
Natural Gasoline Background
Natural gasoline is an NGL on the heavier end of the hydrocarbon spectrum, typically designated as pentanes plus (C5+). It resembles a very light crude or condensate. In the industry, it’s often simply called “natural gasoline” or “plant condensate.”
Key Uses
- Gasoline blending as a light, high-vapor-pressure blendstock
- Diluent for heavy crude oil (especially in Canada’s oil sands, to create “dilbit”)
- Feedstock for petrochemical processes
- Occasionally sold as a standalone fuel component or exported
Production Sources
Natural gasoline is produced mainly from:
- Natural gas processing plants (the heaviest portion of the NGL barrel)
- Stabilization of field condensate during crude oil production (less common in marketed NGL reporting)
The US shale boom has notably increased production, especially from the Permian Basin and Eagle Ford Basin.
Infrastructure & Storage
Natural gasoline is stored in:
- Salt dome caverns and tanks in Gulf Coast hubs (Mont Belvieu is the primary location)
- Field-level tankage in producing regions
- Railcar or pipeline storage during transit to blending or export locations
Pipelines move volumes from production regions to refineries, blenders, or export docks. Rail transport is also common, particularly to Western Canada.
Domestic Demand
The main domestic uses are:
- Blending into finished gasoline to meet vapor pressure and octane specs
- Diluent blending with heavy crude oil from Canada and North Dakota
- Smaller volume into petrochemical production
Diluent demand is especially important: Canadian oil sands operations rely heavily on US natural gasoline to move bitumen by pipeline.
Exports
Exports are focused mainly on:
- Canada (as diluent)
- Some volumes into Latin America and occasional Asian buyers for blending
Canadian diluent demand is the single biggest structural driver of export flows.
Pricing
Natural gasoline prices are typically quoted at:
- Mont Belvieu (primary benchmark)
- Conway, Kansas (Midcontinent benchmark)
Key Pricing Drivers
- Crude Oil Prices Natural gasoline tracks very closely with WTI because of its similarity to light naphtha or condensate.
- Gasoline Blendstock Demand Seasonal blending patterns influence pricing.
- Canadian Diluent Demand Steady, structural demand from Western Canada supports a large baseline consumption.
- Natural Gas/NGL Production Higher shale output increases supply, affecting balances and pricing.
- Inventory Levels Market participants watch stocks to gauge oversupply or tightness.
- Export Economics Pipeline and rail transportation costs into Canada set price floors.
Seasonality
Natural gasoline shows less pronounced seasonality than propane or normal butane but still has patterns:
- Summer Driving Season (April–September): Higher demand for gasoline blending raises prices relative to crude.
- Winter: Decreased recoveries at processing plants, because natural gasoline more readily condenses as part of the crude oil stream.
- Spring and Fall Refinery Maintenance: May cause temporary softening in blending demand.
Overall, seasonal swings are tempered by consistent diluent demand, which anchors baseline consumption levels.
General Market Principles
Strong Crude Oil Correlation Prices often move in tandem with WTI and condensate markets.
Blending and Diluent Dynamics Demand comes from gasoline spec requirements and Canadian bitumen transport needs.
Infrastructure Constraints Pipeline and rail capacity to Canada can cause basis volatility.
Export/Import Economics Netbacks from Canadian oil sands influence pricing spreads.
Inventory Cycles Builds occur in lower demand periods, with draws during blending peaks or pipeline restocking.
Fundamentals
The production of natural gasoline continues to grow at very similar rates to those of propane and butane. Note the seasonal production decreases in winter when natural gasoline remains in the crude oil stream in higher proportions during colder weather because of its high boiling point.
US natural gasoline exports are dominated by shipments to Canada. These exports primarily serve as a critical diluent for Canada's heavy crude oil and oil sands bitumen, thinning the viscous substance so it can flow through pipelines and railcars.
Natural gasoline inventories are shaped by the balance between growing gas-plant supply, gasoline-blending demand and exports, particularly shipments used as diluent in Canada. Inventories generally experience less pronounced seasonal swings than propane or normal butane because diluent demand provides a relatively steady outlet for supply. Rising production can add to stocks when blending and export demand lag, while stronger demand for gasoline blending or diluent can help draw inventories lower.
LPG
LPG
Exports of LPG from the US are critical to allowing for the growing amounts of NGLs from shale. The future of propane and butane prices hinges on the ability for those purity products to reach the water and fulfill overseas demand. If terminal or dock capacity is tight, inventories in the Lower 48 could swell, depending on production growth levels. As mentioned above, higher levels of US inventories typically result in lower prices. Below are planned and existing export terminal additions that will help clear excess propane and butane from the US.
Commentary
November 5: US LPG export economics remained highly dependent on shipping conditions during October, with Houston-to-Chiba VLGC freight holding near record levels. Improving Panama Canal conditions late in the month provided some logistical relief, but longer voyages and limited vessel availability continued to keep freight elevated. Strong Asian propane prices were sufficient to keep the US-to-Asia propane arbitrage open, while spot butane export economics remained more challenged.
October 7: US LPG exports remain critical for balancing continued NGL supply growth, but freight costs reached new highs during September. Houston-to-Chiba VLGC freight averaged approximately $322/mt during the week ended September 25 and reached a record $330/mt as Panama Canal constraints and longer Cape of Good Hope voyages tightened available vessel capacity. The latest EIA data show US propane and normal butane exports totaled roughly 2.6 MMBbl/d in July. While those figures predate the recent freight surge, they highlight the volume of US LPG reliant on international shipping markets.
September 4: US LPG exports remain an important outlet for continued domestic supply growth, but rising shipping costs are making those barrels more expensive to move overseas. Houston-to-Chiba VLGC freight climbed in late August as Middle East security risks, limited vessel availability and continued Asian demand increased tonne-mile requirements. Elevated freight costs could increasingly weigh on US export economics even as international demand for US-origin barrels remains strong.
August 5: Global LPG markets strengthened during July as renewed Middle East tensions supported crude and increased the value of supply originating outside the Arabian Gulf. However, the US propane market remains weighed down by high inventories, limiting the pass-through from stronger international pricing into Mont Belvieu. Houston-to-Chiba VLGC freight rates declined during July but remained historically elevated. Longer voyages, including rerouting around the Cape of Good Hope, and stronger tonne-mile demand from Asia and India continue to absorb available shipping capacity.
July 10: US LPG markets softened through June as lower crude oil prices and the normalization of Strait of Hormuz trade flows narrowed export arbitrage into Asia. The unwinding of the geopolitical risk premium weighed on international LPG prices, while elevated VLGC freight costs and rising domestic propane inventories further pressured export economics. Despite these near-term headwinds, Gulf Coast export infrastructure continues to expand, positioning the US to accommodate growing propane and butane production over the coming years. While increased Arabian Gulf competition may limit incremental export growth, overseas demand remains the primary outlet for balancing the expanding US NGL barrel.
Recent market-related events
November 5: The Panama Canal Authority added another Neopanamax booking slot in October as Gatun Lake levels improved. Better canal access reduced the need for some VLGCs to reroute around the Cape of Good Hope, providing an early sign that shipping constraints could begin to ease.
October 7: Repauno’s Phase 2 expansion in southern New Jersey is expected to begin operations in early 2027, adding approximately 72 MBbl/d of LPG export capacity and bringing total terminal capacity to roughly 96 MBbl/d. The expansion provides Northeast NGL producers with another route to waterborne markets outside of Marcus Hook and Gulf Coast terminals, although East Daley expects utilization to ramp gradually rather than immediately reach full capacity.
July 10: Energy Transfer announced an expansion of its Nederland export terminal that will add approximately 240 MBbl/d of ethane export capacity and 55 MBbl/d of additional LPG export capacity beginning in 2028. The expansion reflects continued expectations for long-term growth in US NGL production and export demand.
June 23: Phillips 66 has quietly expanded fractionation capacity at its Sweeny Complex by 125 MBbl/d, increasing total capacity to 675 MBbl/d from 550 MBbl/d. The company is also advancing its proposed 100 MBbl/d Coastal Bend fractionator, which is expected to enter service in 1Q28. Combined, the projects would add 225 MBbl/d of Gulf Coast fractionation capacity, positioning Phillips 66 to accommodate growing NGL production from the Permian and Eagle Ford basins.
June 4: Targa recently started up a new fractionator at Mont Belvieu and remains on track to expand both NGL takeaway and LPG export capacity through 2027. Enterprise is likewise expanding gas processing, fractionation, pipeline, and export infrastructure, including commissioning Phase 2 of its Neches River Terminal, which can load propane or ethane depending on market conditions. Collectively, these projects reflect expectations that associated gas and NGL production will continue growing even if Permian crude oil production remains relatively flat.
Background on US LPG Exports
The United States has become the world’s leading LPG exporter over the past decade, largely because of the shale boom that dramatically increased natural gas liquids (NGL) production. When natural gas and crude oil are produced, significant volumes of NGLs, especially propane and butane, are extracted along with them.
Domestic demand for propane (e.g., heating, agriculture, petrochemicals) and butane (e.g., blending, refining, petrochemicals) has limits and is seasonal. As shale output surged, US producers faced the risk of oversupply and low domestic prices. LPG exports emerged as the critical pressure valve to balance the market.
The Gulf Coast, with major fractionation hubs (like Mont Belvieu) and deepwater export terminals, became the launch point for large-scale shipments to Asia, Latin America, and Europe. These exports have grown to over 2.5 MMBbl/d (waterborne and land exports) in recent years, making them essential for:
- Clearing surplus production of propane and butane that the US market cannot absorb year-round.
- Supporting domestic NGL values relative to crude oil by tapping higher-value overseas demand, particularly from Asian petrochemical and heating markets.
- Creating price linkages between US hubs and international benchmarks (like FEI in Asia).
In effect, LPG exports are no longer optional—they are fundamental to balancing US propane and butane supply. Without strong export flows, inventories could quickly swell, pressuring prices and reducing NGL recovery incentives across the upstream and midstream sectors.
chart_pack
Chart Packet
Want this in your inbox?
AEGIS market analysts publish research across crude, natural gas, NGLs, refined products, metals, and rates.
Subscribe to research