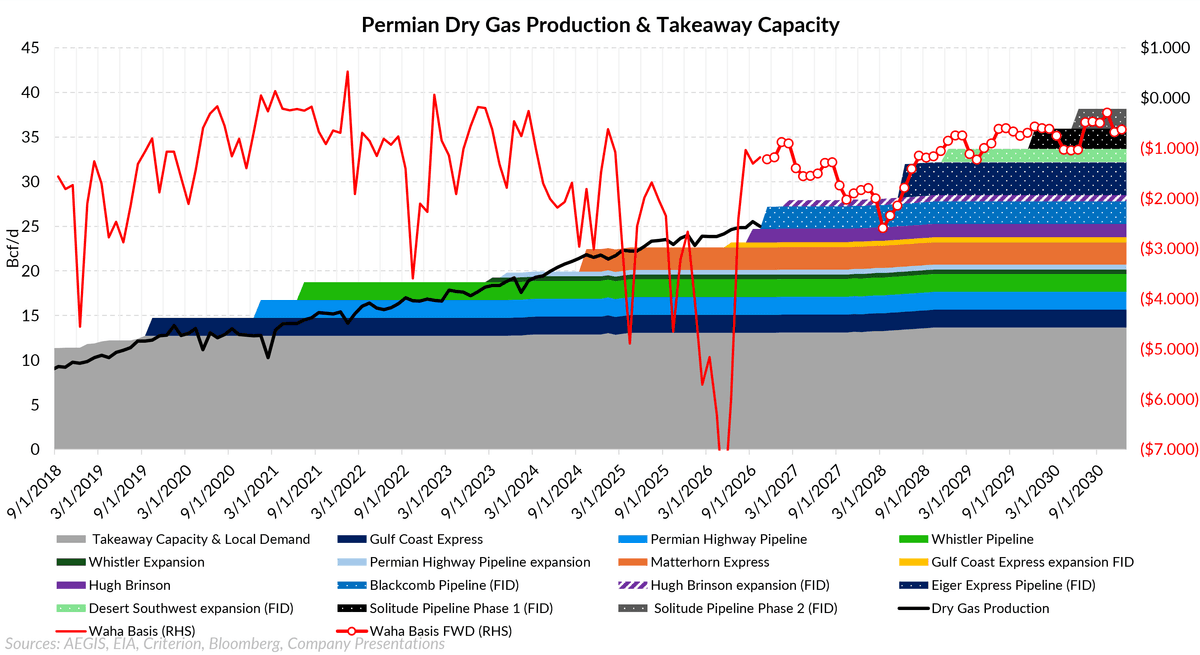
The Permian Basin has operated near the limits of available natural gas egress capacity for several years, resulting in periods of steep regional price discounts. Conditions have improved recently as new takeaway capacity has entered service ahead of schedule. Roughly 4.5 Bcf/d of new outbound pipeline capacity is expected to enter service this year. Low spot prices also led to an accumulation of economically driven gas shut-ins during the spring, which helped reduce pressure on the system, but resulted in low prices. The next period with the greatest risk of renewed constraints appears to be early 2028, before another wave of pipeline capacity is scheduled to come online. The tightening of the Waha–Henry Hub spread through 2030 reflects growing confidence that incremental pipeline additions will materially reduce the risk of prolonged system congestion.
Get continuous updates and actionable insights with our regularly updated Permian Basin report.
Commentary
November 6: Waha cash fell for three straight sessions, from $1.46/MMBtu on October 30 to $1.12 on November 4, its lowest print since early September, before rebounding 27 cents to $1.39 on November 5. November cash has averaged about $1.32 so far. The forward curve was far steadier, with every seasonal strip moving less than 4 cents from October 30 to November 5. December basis was nearly unchanged at -$1.22, the balance of Winter ’26/’27 (December through March) eased 1.8 cents to -$1.15, Summer ’27 improved 3.6 cents to -$1.57, and Winter ’27/’28 firmed 2.6 cents to -$2.08. Spring 2028, still the weakest part of the curve, held near -$2.41. In infrastructure news, Energy Transfer said on November 3 that Phase II of its Hugh Brinson Pipeline, which adds downstream compression, will lift capacity from about 1.5 Bcf/d to more than 2.3 Bcf/d and is expected in service in the first quarter of 2027. Phase I entered full service on September 1, and the company said it continues to see interest from customers seeking to increase commitments and new customers looking for Permian egress. Energy Transfer also placed its 275 MMcf/d Mustang Draw II processing plant in the Midland Basin into service in October and announced plans for Bear II, a 200 MMcf/d Delaware Basin plant due in the third quarter of 2027. AEGIS notes the roughly 0.8 Bcf/d added by Phase II arrives well ahead of spring 2028, while new processing plants keep adding gas that will need a way out of the basin.
November 2: The Waha basis forward curve gave back part of last week’s rally, with every seasonal strip moving lower. From October 23 to October 30, the balance of Winter ’26/’27 (December through March) fell 5.6 cents to -$1.13/MMBtu, Summer ’27 slipped 6.0 cents to -$1.60, and Winter ’27/’28 dropped 9.7 cents to -$2.11. Winter ’27/’28 now sits about 39 cents below its July 24 level. Unlike last week, basis weakened alongside Henry Hub. December, now the prompt month, saw Waha basis slip 7.3 cents to -$1.225 as NYMEX December fell 15.2 cents to $2.90, leaving December Waha fixed price down 22.5 cents at $1.67. Waha cash also softened, falling from $1.585 on October 23 to $1.46 on October 30 after touching $1.27 on October 29, its lowest print of the month. October cash averaged about $1.63. In midstream news, ONEOK said on its October 28 earnings call that it is earning less from buying gas at Waha and selling it at Katy, as additional Permian egress has narrowed the spread between the two hubs. Its natural gas optimization and marketing earnings fell $63 million from the second quarter, mostly on the narrower Waha-Katy differential, and it expects a further reduction in the fourth quarter. ONEOK processed a record 1,614 MMcf/d of Permian gas in the third quarter and has another 1.06 Bcf/d of Permian processing capacity scheduled through the third quarter of 2027. AEGIS notes that rising processed volumes could test Permian egress again before Eiger Express arrives in mid-2028, consistent with the curve’s weakness in spring 2028.
October 23: The Waha basis forward curve reversed course this week, strengthening across every seasonal strip and ending five straight weekly declines in Summer ’27 and Winter ’27/’28. From October 16 to October 22, Winter ’26/’27 improved 23.0 cents to -$1.12/MMBtu, Summer ’27 gained 22.6 cents to -$1.57, and Winter ’27/’28 rose 17.7 cents to -$2.03. Even so, Winter ’27/’28 remains about 31 cents below its July 24 level. Prompt November basis jumped nearly 32 cents to -$1.23, but the gain likley came from a weaker Henry Hub: NYMEX November fell 32 cents to $2.80, while November Waha fixed price was essentially unchanged at $1.57. Further out, the move was more than a Henry Hub story, with Summer ’27 Waha fixed price up 12 cents. Waha cash held in a tight range, slipping 3 cents from $1.73 on October 16 to $1.70 on October 22, with a low of $1.655 on October 19. In infrastructure news, Kinder Morgan said on October 21 that NGPL reached a final investment decision on Permian Link, a $4.2 billion, 434-mile pipeline that will move about 2.8 Bcf/d northbound from the Permian toward the Texas Panhandle. The project is supported by long-term take-or-pay agreements tied to new power generation for an A-rated hyperscaler and is expected in service in the third quarter of 2030. AEGIS notes the added takeaway arrives well after spring 2028, when we see the greatest risk of renewed Permian egress constraints.
October 16: The Waha basis forward curve weakened again week-over-week, with every seasonal strip moving lower. From October 9 to October 15, Winter ’26/’27 fell 9.4 cents to -$1.37/MMBtu, Summer ’27 slipped 5.9 cents to -$1.82, and Winter ’27/’28 dropped 7.5 cents to -$2.21. Since July 24, Winter ’27/’28 has now given up almost 50 cents. Prompt November basis declined 6.8 cents to -$1.62, even as NYMEX November edged up 1.6 cents, pulling November Waha fixed price down about 5 cents to $1.62. Oil continued to strengthen alongside the decline, with the Cal 2027 WTI strip rising $2.78/bbl on the week to $86.24/bbl, which may be adding to expectations for more associated gas. The October Waha gas cash price was little changed, marked near $1.68. In midstream news, Energy Transfer announced on October 6 that it will acquire Vaquero Midstream for about $2.6 billion. Vaquero’s Caymus complex in the Delaware Basin processes about 675 MMcf/d, with room to expand to about 1.2 Bcf/d. AEGIS notes the deal adds processing capacity, not egress, in a basin where the next major takeaway project is not expected until mid-2028.
October 8: The Waha basis forward curve continued to decline week-over-week. Seasonal strips have been falling since the curve reached recent highs in late July. Since July 24, Winter ’26/’27 has declined 19.6 cents, Summer 2027 has fallen 30.3 cents, and Winter ’27/’28 has dropped 38.9 cents. Recent strength in oil prices may be contributing to expectations for more associated gas production in the Permian. Over the same July-to-October period, the Cal 2027 WTI strip has risen almost $8/bbl to $81.52/bbl. Winter ’27/’28 has seen the largest decline in Waha basis, as the next major pipeline following the current round of additions is not expected online until around mid-2028. Downward pressure on the Waha basis forward curve is most acute during periods without new takeaway capacity. In infrastructure news, Summit Midstream’s Double E compression expansion is poised to increase intrabasin gas mobility, giving Delaware Basin supply greater access to the Waha hub. The expansion is expected online in October 2028.
October 2: Cash prices at Waha fell for five consecutive sessions, declining from $2.08 on September 24 to $1.665 on October 1. The Waha basis forward curve also weakened, slipping a few cents week-over-week. Permian dry gas production reached a monthly record of 25.6 Bcf/d in September, according to S&P data, with a single-day record of 26.2 Bcf/d. In infrastructure news, FERC extended the deadline to complete Saguaro Connector’s border facilities to February 15, 2030. Saguaro Connector Pipeline LLC requested the three-year extension in April 2026, citing ongoing commercial negotiations, litigation, and delays at the downstream LNG terminal. The proposed pipeline would connect Permian gas supplies with Mexico’s Sierra Madre pipeline, ultimately supplying feed gas to Mexico Pacific’s proposed Saguaro Energía LNG export facility in Puerto Libertad, Sonora, on the Gulf of California.
September 25: Waha cash prices rose for four consecutive sessions, from $1.70/MMBtu on September 18 to $2.08/MMBtu on September 24. The Waha basis forward curve moved in the opposite direction, weakening by 8–15¢ across several seasonal strips. Spring 2028 remains the weakest part of the curve, when we see the greatest risk of renewed Permian egress constraints just before Eiger Express enters service.
Waha Basis Outlook and Notes
Winter '26-'27 & Summer '27
Both Blackcomb and Hugh Brinson will add over 4 Bcf/d of new eastbound capacity from the Permian. How quickly these pipelines fill will depend on how much gas producers have ready to bring online. It is more realistic that some open capacity will remain after these expansions - especially on Hugh Brinson. The overbuild dynamic extends into 2027. The Waha forward curve reflects this outlook, pricing at a narrower discount to Henry Hub during this period due to the expectation of excess takeaway capacity from the Permian.
Winter '27-'28 & Summer '28
During this period, Permian egress could be most at risk. Eiger, expected to enter service in mid-2028, is the next major takeaway project. The Waha forward curve is weakest in spring 2028, reflecting the risk that rising production will fill the pipelines added in the second half of 2026 and create renewed constraints in the first half of 2028. The curve then snaps back to a narrower discount around the time Eiger is expected to enter service, as the project reduces the risk of Permian takeaway constraints.
Winter '28-'29 to 2031
Roughly 16 Bcf/d of new pipeline capacity is under development or has come online since summer 2026 to help move gas out of the basin. It is possible the Permian may enter an overbuild phase through parts of the remainder of the decade, easing system constraints and reducing the likelihood of the severely depressed prices observed in 2024 and 2025. Eastbound capacity may fill by late 2027 to early 2028. One caveat: Producers in the region with whom we speak generally believe operators will ultimately fill all of this new pipeline capacity. This time different?
For more discussion on basis price moves and the current forward curves:
For more discussion and charts, jump to our outlook and chart pack. Remember, the local market is influenced by the broader gas market. Consult our Gas Macro Outlook for more.
Historical Pricing Regimes
Waha has continuously disappointed compared to the forward curve
Over the past 10 years, Waha basis has generally settled below the price that was available to hedge 12 months earlier. In most cases, the forward market priced Waha basis too optimistically, resulting in settlements that were weaker than what producers could have locked in a year in advance.

The chart compares the Waha forward price from 12 months earlier (dashed red line) to the monthly IFERC Waha settlement (light blue line). The gold bars represent the difference between the two. Gold bars below zero indicate periods when producers would have benefited financially by hedging Waha basis 12 months in advance rather than remaining exposed to the monthly IFERC settlement. Conversely, there were periods—most notably during and immediately following COVID, as well as portions of 2023—when remaining unhedged would have produced a better outcome.
The primary exceptions occurred when relatively weak production growth coincided with the addition of new pipeline capacity, allowing takeaway infrastructure to catch up with supply growth. We have excluded the impact of Winter Storm Uri from this analysis, as it was an extraordinary event that materially distorted pricing and is unlikely to be representative of future market conditions.
While historical performance does not guarantee future results, understanding how Waha basis has behaved through different market cycles provides useful context for evaluating current forward pricing. Some market participants argue that the Permian could face an overbuild of pipeline capacity through the end of the decade, potentially supporting stronger basis levels. At the same time, there are compelling arguments that natural gas production growth could continue to surprise to the upside. Analysts point to aging wells becoming increasingly gas-rich, rising gas-to-oil ratios (GORs) in newer wells, and the potential for higher oil prices to drive additional associated gas production.
Stepping back and focusing on what the last decade of data demonstrates, the evidence suggests that producers would have generally been better off hedging Waha basis at least 12 months forward rather than remaining fully exposed to monthly IFERC settlements. While there have been notable exceptions, they have been relatively infrequent compared to the broader historical trend.
Recent Market-Relevant Events
08.17.2026
Solitude Pipeline System reaches FID
07.31.2026
Blackcomb flowing gas ahead of schedule
07.17.2026
Hugh Brinson Pipeline starts service ahead of schedule
Infrastructure Outlook
The basin suffers from persistent oversupply compared to the amount of egress pipeline capacity. This affects the gas market more than it does crude oil, mostly because of aggressive additions in oil takeaway due to oil’s larger revenue share for almost all operators in the area.
As of 10/23/2026
For a discussion of production outlook:
Below are the most market-relevant infrastructure projects that appear to be funded and going forward. The projects that offer intra-region capacity (egress) are also shown in the chart above.
Note: Deeper discussion included below the map.
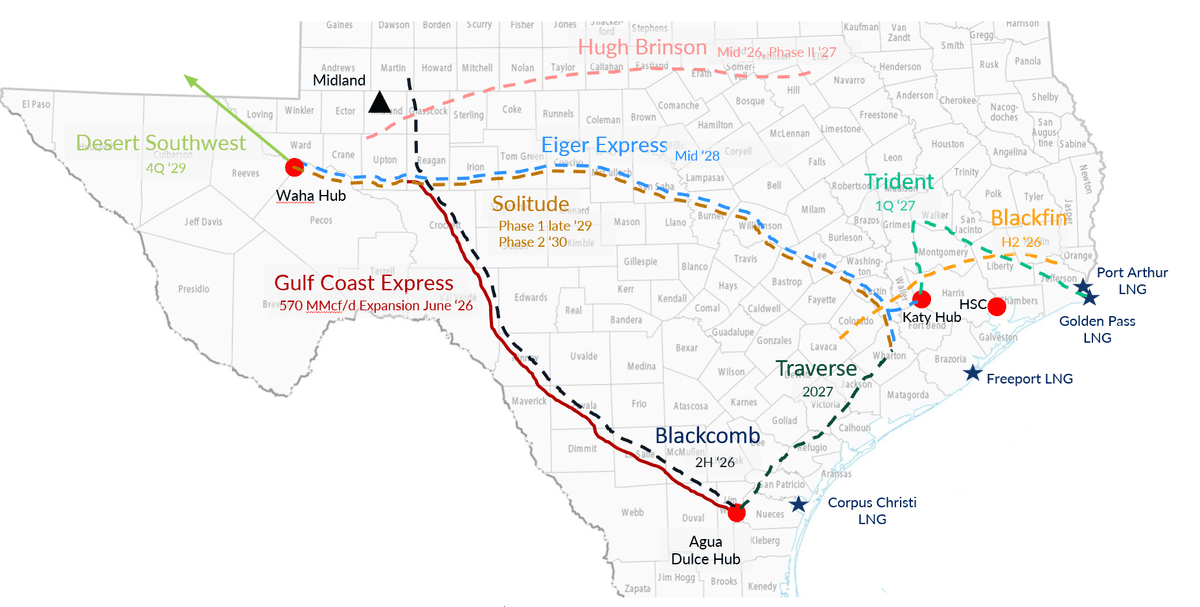
Gas Pipeline Projects
Gulf Coast Express (Expansion)
In-service date: 2Q 2026
Capacity: 0.57 Bcf/d

Source: Kinder Morgan
Gulf Coast Express Expansion - Kinder Morgan announced the start of an open season for the Gulf Coast Express expansion on May 16, 2022. The project entails adding compressors to the GCX pipeline to enhance its capacity from the Permian Basin to South Texas markets by 570 MMcf/d. The project is expected to be operational mid-2026, subject to additional customer agreements. Kinder's 3Q 2025 earnings call deck showed a 2Q26 in-service date.
Blackcomb
In-service date: 4Q 2026
Capacity: 2.5 Bcf/d

Source: WhiteWater
Blackcomb - WhiteWater Midstream and Targa are moving ahead with building a new 42-inch, 365-mile natural gas pipeline from the Permian Basin in West Texas to the Agua Dulce hub in South Texas. The startup timeline is 2H 2026 and will transport up to 2.5 Bcf/d.Shippers include Devon, Diamondback Energy, Marathon Petroleum, and Targa. Will source in the Midland Basin and the 3 Bcf/d Agua Blanca pipeline system in the Delaware Basin owned by WhiteWater and MPLX.
Hugh Brinson
In-service date: Q3 2026
Capacity: 1.5 Bcf/d

Source: Energy Transfer
Hugh Brinson - The Hugh Brinson Pipeline Project, formally know as Warrior, will be built in two phases. Phase I consists of roughly 400 miles of 42-inch pipeline running from Waha and the Midland Basin to Maypearl, Texas. The majority of the pipe steel has been secured and is being manufactured in U.S. mills. Phase I is designed for about 1.5 Bcf/d, is fully sold out under long-term, fee-based commitments with investment-grade counterparties, and will use Energy Transfer’s network south of the DFW metroplex to reach major trading hubs and markets. In-service is targeted for Q4 2026. Phase I also includes the Midland Lateral—a 42-mile, 36-inch line that will connect Energy Transfer processing plants in Martin and Midland counties to the mainline. Phase II adds compression, creating a bi-directional system able to move roughly 2.2 Bcf/d from west to east and about 1 Bcf/d from east to west. At start-up, more than 2.2 Bcf/d is expected to be under contract. Total capital for Phases 1 and 2 is estimated at approximately $2.7 billion. Source: ET
Hugh Brinson Expansion
In-service date: 1Q 2027
Capacity: 0.7 Bcf/d

Source: Energy Transfer
Hugh Brinson Expansion - Phase II adds compression, creating a bi-directional system able to move roughly 2.2 Bcf/d from west to east and about 1 Bcf/d from east to west. At start-up, more than 2.2 Bcf/d is expected to be under contract. Total capital for Phases 1 and 2 is estimated at approximately $2.7 billion. Source: ET
Energy Transfer Transwestern Desert Southwest Pipeline Expansion Project
In-service date: Q4 2029
Capacity: 2.3 Bcf/d

Source: Energy Transfer
Desert Southwest Pipeline Project - The Desert Southwest Pipeline Project is a 516-mile, newly upsized 48-inch diameter natural gas pipeline that will increase system capacity to up to 2.3 Bcf/d, depending on the final compression configuration. The project is designed to serve strong and growing natural gas demand across the Desert Southwest region. Following the upsizing, total project costs are now estimated at up to approximately $5.6 billion, excluding Allowance for Funds Used During Construction (AFUDC). Energy Transfer continues to target an in-service date in the fourth quarter of 2029. Source: Energy Transfer
Eiger Express Pipeline
In-service date: Mid 2028
Capacity: 3.7 Bcf/d
Source: WhiteWater
Note: Pipe footprint is the same as Matterhorn.
Eiger Express Pipeline - The Eiger Express Pipeline is designed to transport up to 3.7 billion cubic feet per day (Bcf/d) of natural gas through approximately 450 miles of 48-inch pipeline from the Permian Basin in West Texas to the Katy area. Supply for the Eiger Express pipeline will be sourced from multiple connections in the Permian Basin, including gas processing facilities in the Midland Basin, and from the Delaware Basin via the Agua Blanca Pipeline, a joint venture between WhiteWater, Enbridge and MPLX. Source: WhiteWater
Solitude Pipeline System
In-service date: Late 2029 and 2030
Capacity: 2.25 Bcf/d Phase I and 2.25 Bcf/d Phase II
Source: WhiteWater
Note: Pipe footprint is the same as Eiger and Matterhorn.
Eiger Express Pipeline - The Solitude Pipeline System will be two 48" natural gas pipelines, each running from the Permian Basin to Katy, Texas. The joint venture will be a phased desgin that provides initial capacity of 2.25 Bcf/d in late 2029, and an additional 2.25 Bcf/d in 2030, with the ability to increase capacity therafter. Source: WhiteWater
Other Projects
Kinder Morgan's Copper State Connector (no FID) - The proposed project is a 630-mile, 42-inch greenfield pipeline capable of transporting 2.1 billion cubic feet per day (Bcf/d) from Waha to Arizona. During Kinder Morgan’s Q2 2025 earnings call, company representatives appeared to downplay the initiative when questioned by analysts, citing a competitive environment and uncertainty regarding tariff costs. Click here for the link to Kinder's comments in Docket G-00000A-25-0029 filed in February 2025 with the Arizona Corporation Commission.
Saguaro Pipeline (2028 no FID) - The pipeline is proposed to run from the Waha Gas Hub in the Permian Basin in West Texas, U.S. to the Mexican border in Hudspeth County, Texas. The pipe would be 2.8 Bcf/d at 48" diameter, owned by ONEOK. This pipe's future depends on whether Mexico's Pacific LNG reaches FID (this keeps getting delayed. If this is built, the Permian has more of a chance to be overbuilt with takeaway pipe through 2030.
Northbound Pipeline Expansions
Transwestern - Expansion of 80 MMcf/d. In-service by November 2026.
Local Supply
Based on public operator guidance, midstream company outlooks, pricing trends, and recent drilling activity, we anticipate continued growth in both oil and gas production in the Permian Basin, albeit at a slower pace than in the past two years. Historically, Permian gas supply has closely followed available pipeline takeaway capacity, meaning gas is always waiting when infrastructure allows. However, the trajectory of future oil supply growth may be more measured, as operators exhibit greater capital discipline. This moderation in oil production could result in a flatter gas supply growth profile, even with rising gas-to-oil ratios (GOR) and increased drilling in lower-liquids areas.
Production
Operator Guidance
Diamondback Energy (Q2 2026 EC)
08/04/2026
2026 Guidance:
Q2 2026 gas realizations were negative $2.15 per Mcf pre-hedge, driven by insufficient Waha takeaway capacity
Spring pipeline maintenance drove Waha to a record low of roughly negative $10 per Mcf during the quarter
Waha turned positive in July and has held up since, as new takeaway began flowing
Strategic & Infrastructure Highlights
Secured long-haul takeaway to the Gulf Coast is expected to more than double by year-end 2026, structurally shifting price exposure toward larger demand hubs
The gas offload strategy cut flaring an estimated 24% sequentially and protected roughly 1,400 MBO of oil that would otherwise have been choked back
A large shovel-ready gas-to-power project is in development, with details deferred until a long-term contract with a credible counterparty is signed
Management ties long-term Permian gas monetization to LNG buildout and power generation
Drilling & Basin Activity:
Gas production continues to outperform expectations, with the Barnett becoming a larger share of the development program
Improved local gas marketing and strategic pipeline split-connects, not well selection, cited as the biggest driver of realization improvement
Analyst Q&A Takeaways:
Waha basis hedges layered on over the last couple of years are credited with insulating realizations from the negative pricing complex
Waha and HSC basis protection covers roughly 55% of estimated 2026 gas production; outright gas price protection covers over 60%
Q3 2026 Waha basis swaps of 650,000 MMBtu/d at a $(1.87) per MMBtu differential
Devon Energy (Q2 2026 EC)
08/05/2026
2026 Guidance:
Permian gas volumes of 1,274 MMcf/d in Q2 2026, Devon's largest single-basin gas volume
Delaware Basin gas realizations "were depressed by regional Waha pricing driven by infrastructure constraints in the Delaware Basin"
Full-year 2026 company gas guidance of 3,300–3,400 MMcf/d, with no basin split disclosed
Strategic & Infrastructure Highlights:
The Coterra merger closed May 7, 2026, making Q2 the first combined reporting quarter
Added 16,300 net acres and roughly 400 locations in the Delaware Basin through a federal lease sale
No Waha takeaway project, incremental capacity, or curtailment volume was disclosed this quarter
No LNG offtake or in-basin power deal tied to Permian gas appears anywhere in Devon's Q2 materials
Drilling & Basin Activity
Company-wide activity averaged 34 operated rigs and 10 completion crews, with no Permian split disclosed
The Q2 oil beat of 503 MBOD was driven primarily in the Delaware Basin
The Permian remains the largest regional capital allocation at roughly 62% of upstream spending
Analysts Q&A Takeaways:
Waha basis swaps of 350,000 MMBtu/d for Q3–Q4 2026 at $(1.86) per MMBtu against Henry Hub
Full-year 2027 Waha basis swaps of 135,041 MMBtu/d at $(1.30) per MMBtu
Kinetik Holdings (Q2 2026 EC)
08/06/2026
2026 Guidance:
Q2 2026 processed gas volumes of 1.74 Bcf/d, flat year over year despite an estimated 250 MMcf/d of Waha price-related processed gas shut-ins
Curtailment assumption cut to roughly 25 MMcf/d on average for the second half of 2026, against the roughly 220 MMcf/d full-year figure assumed a quarter earlier
2026 processed gas volume exit rate guided to nearly 2.2 Bcf/d, an increase of about 20% exit to exit
Full-year processed volume growth guidance raised to a mid- to high-single-digit percentage
Full-year 2026 Waha Hub price assumption of $(0.26) per MMBtu on the July 28, 2026 strip, still negative on a full-year average
Drilling & Basin Activity:
The ECCC Pipeline was placed into service, establishing a north-to-south connection across the western system between Eddy and Culberson counties
Right-of-way procurement is underway for an anticipated 2027 ECCC expansion tied to continued New Mexico customer growth
The acid gas injection and sour-gas conversion project remains on schedule for a year-end 2026 start-up
Kings Landing II reached FID in May 2026 and is now expected to complete in mid-2028, earlier than previously communicated
Following Kings Landing II, total Delaware North sour gas processing capacity will exceed 700 MMcf/d
Strategic & Infrastructure Highlights:
Secured incremental firm residue gas access to Gulf Coast markets beginning in 2027, plus new residue gas and NGL transportation agreements supporting the Delaware North complexes
The board authorized long-lead equipment procurement for the next processing expansion beyond Kings Landing II
Substantially hedged through year-end at the top of the 40%–80% target range, with incremental protection added opportunistically in Q2
Analysts Q&A Takeaways
Management said Waha pricing has recovered from the extreme dislocations of the first five-plus months of 2026, with basis differentials tightening
Gulf Coast marketing gains that offset weak Waha pricing in the first half are expected to moderate in the second half as curtailed volumes return
Management cited LNG exports, power generation, and data center development as the demand drivers behind continued volume growth
Management noted more than 11 Bcf/d of new Permian basin egress capacity sanctioned through 2029
Energy Transfer (Q2 2026 EC)
08/04/2026
2026 Guidance:
Hugh Brinson is in commercial service and expected to flow its full Phase I capacity of 1.5 Bcf/d by September 1, 2026
Permian gathered volumes rose 4%, with NGL output up on higher plant utilization at new and existing plants
Two Texas customers added a combined 100 MMcf/d to existing contracts for power plant or data center sites
Strategic & Infrastructure Highlights
Hugh Brinson Phase II compression lifts capacity to roughly 2.2 Bcf/d west-to-east, targeted around the first quarter of 2027
Desert Southwest: roughly 520 miles of 48-inch pipe at up to 2.3 Bcf/d, targeting Q4 2029, with FERC scoping meetings complete and a certificate application expected in Q4 2026
Mustang Draw I, 275 MMcf/d, entered service in the Midland Basin in June 2026; Mustang Draw II, also 275 MMcf/d, is targeted for Q4 2026
Springerville Lateral: roughly 120 miles of 30-inch pipe at 625 MMcf/d, extending Transwestern to serve generation replacing two coal plants, targeting Q4 2029
Permian NGL takeaway is running roughly 95% utilized, leaving limited spare capacity
Drilling & Basin Activity:
Management says Hugh Brinson has unleashed pent-up Permian gas, including shut-in volumes and drilled-uncompleted wells producers had held back
Waha basis has narrowed faster than the company expected
Permian gas volumes seen reaching roughly 4.5 Bcf/d by the first quarter of 2027 as new egress opens
Analysts Q&A Takeaways:
The first of four new connections serving power-plant load, roughly 300 MMcf/d, is already in service
Negotiations are nearing completion on roughly 250 MMcf/d of new Oklahoma power-plant demand
Additional natural gas pipeline project announcements are expected later this year to serve growing power demand
Occidental Petroleum (Q2 2026 EC)
08/06/2026
2026 Guidance:
Permian net gas production of 1,106 MMcf/d in Q2 2026, within total Permian production of 804 Mboe/d
Permian production guided to 795–815 Mboe/d for Q3 2026 and 801–817 Mboe/d for the full year, a narrower range on an essentially flat midpoint
Q2 Permian production of 804 Mboe/d came in above the 783–803 Mboe/d range guided on the Q1 call
Gas is guided at 27.1% of total company production for Q3 2026 and 27.0% for the full year
Strategic & Infrastructure Highlights
Domestic realized natural gas price averaged negative $1.48 per Mcf in Q2 2026, against positive $1.01 per Mcf in Q1
Segment results were described as helped by higher realized crude prices and partially offset by lower domestic natural gas prices
Midstream and marketing guidance cites reduced Western Midstream ownership from the Q1 2026 gas gathering contract update as a driver of segment variance
No Waha, basis, curtailment, or takeaway commentary appears in the Q2 release or slide deck
Drilling & Basin Activity:
Permian 2026 plan of roughly 19 gross rigs, about 14 net, against roughly 20 gross rigs guided a quarter earlier
Permian wells online guided to 485–515 for 2026, up from the 460–510 range guided on the Q1 call
No Permian frac crew count was disclosed
Analysts Q&A Takeaways:
Management reported a "significant narrowing of the Waha to Gulf Coast spread"
Cited that 3 Bcf of egress capacity has come online this year from the Permian, with 2 Bcf more coming by the end of Q4
Q2 upstream domestic realized gas price of roughly negative $1.50 per Mcf was about $2.50 worse than Q1, a swing attributed directly to the wider Q2 Waha-to-Gulf Coast spread
The Permian program drops three rigs in Q4 2026 on drilling efficiency while still bringing 15 more wells online than planned
Rig Count
Local Demand
The Permian Basin is a supply zone with limited local demand relative to other areas in the US. Local gas demand can range from 400 MMcf/d and 700 MMcf/d depending on the season.
Power Market Influences
Wind and Solar Projects: The Permian Basin's sunny climate and high wind speeds make it an attractive location for renewable energy development. This increases competition in the power market and influences grid dynamics.
Infrastructure Limitations: Limited transmission capacity can bottleneck power flows from generation sites (e.g., gas plants or renewables) to demand centers.
Congestion Pricing: Transmission constraints often lead to price volatility and localized pricing spikes.
Market Design: The Permian Basin straddles the boundaries of the Electric Reliability Council of Texas (ERCOT) and the Southwest Power Pool (SPP), each with different market designs and rules that influence pricing and operations.
Environmental Regulations: Policies targeting emissions and flaring can shift market dynamics by incentivizing renewable energy or penalizing gas flaring.
Data Centers and Electrification: The rise of data centers and electrification of oilfield operations (e.g., electric drilling rigs) also adds to power demand.
Chart Packet
Recent Market-Relevant events
Devon Reaches FID on Solitude Pipeline
- Market Impact: Moves 4.5 Bcf/d of Permian Supply out of the basin
- 2.25 Bcf/d in phase one (2H29) and a second 2.25 Bcf/d in phase two (2030)
- Two 48-inch lines from the Delaware Basin to Katy, Texas
- Katy delivery point stacks more supply into HSC and the Texas/Louisiana LNG corridor alongside Matterhorn and the planned Eiger Express, which should tighten the Waha-Katy spread while adding downstream competition at the Gulf Coast hubs
- Five other projects add roughly 11 Bcf/d out of the Permian by 2029, so Solitude could tip the balance to surplus egress
WhiteWater's Blackcomb project begins commissioning
- Market Impact: Opens up capacity for gas producers in the Permian and strengthens Waha pricing
- Enbridge's CEO said that they "began commissioning the Blackcomb Pipeline during the quarter"
- The 42-inch, 2.5 Bcf/d line from the Midland Basin to Agua Dulce, entering service in phases with the mainline and two compressor stations online this year and capacity ramping through 2027
- Energy Transfer said some early flows on the greenfield Blackcomb Pipeline helping lift Permian prices and production
- MPLX mentioned that in July, the compay began commissioning activity on the Blackcomb Pipeline, "with full commercial service "still scheduled to begin in the fourth quarter"
Energy Transfer's Hugh Brinson Pipeline Starts Service
- Market Impact: Opens up capacity for gas producers in the Permian and strengthens Waha pricing
- The Hugh Brinson Pipeline said intra-state flows began on June 13th
- The project runs from the Waha area in the Permian to Maypearl, south of Dallas. The project includes a 42-mile, 36-inch lateral connecting the main line to processing facilities around Midland and nine interconnects
- The ramp up in gas flows on Hugh Brinson will probably be in stages as the entire system is not scheduled to be fully operational until March 1st 2027
Northern Natural Gas Requests FERC Approval for 361 MMcf/d Permian Expansion
- Market Impact: Would add 361 MMcf/d of takeway capacity / local demand for the Permian
- The expansion will privode firm transport to Southwestern Public Service Company's Gaines County Generating Station in Texas via a new 15-mile lateral
- The project will also interconnect with Transwestern Pipeline in Lea county
- If granted FERC certificate on time, the commissioning of the generation facility would be May 2028 in-service
- FERC Docket CP26-534-000
Energy Transfer to Upsize Desert Southwest Expansion Project
- Market Impact: The addtional capacity on ET's expansion will create additonal egress out of the Permian basin at the end of the decade. The expansion adds to a growing list of pipeline projects aimed at increasing natural gas takeaway capacity out of West Texas and southeastern New Mexico.
- Energy Transfer upsized the pipeline in late 2025 to 2.3 Bcf/d from 1.5 Bcf/d due to customer interest.
- The pipeline will now be a 48" pipe versus the smaller 42" that was orginally planned.
- "The Transwestern Desert Southwest Pipeline expansion will help enable us to meet the region's growing power needs and strengthen Arizona's energy infrastructure" - ET
- The company still expects a Q4 2029 in-service date.
WhiteWater announces new Permian-to-Katy Natural Gas Pipeline
- Market Impact: The pipeline is likley to follow Matterhorn's easement as the pipeline will be operated by WhiteWater and flows to Katy, Texas. Gas reaching the Katy area will soon have the capability to connect to both Blackfin and Trident that will take gas around Houston toward growing LNG demand.
- The Eiger Express Pipeline is designed to transport up to 2.5 billion cubic feet per day (Bcf/d) of natural gas through approximately 450 miles of 42-inch pipeline from the Permian Basin in West Texas to the Katy area.
- Design capacity of the pipeline is 2.5 Bcf/d and estimated in service date by 1H 2028.
- The Eiger Express Pipeline is a joint venture owned 70% by the Matterhorn JV, 15% by ONEOK, and 15% by MPLX. ONEOK's and MPLX's direct ownership interests in the Eiger Express Pipeline joint venture are incremental to their ownership through the Matterhorn JV, resulting in 25.5% and 22% ownership in the pipeline, respectively.
- The Eiger Express Pipeline will be constructed and operated by WhiteWater and is expected to be in service in mid-2028, pending the receipt of customary regulatory and other approvals.
Energy Transfer to Build $5.3 Billion Texas-to-Arizona Gas Pipeline
- Market Impact: Would provide more natural gas takeway capacity for the Permian basin. It would also better supply the desert southwest and possibly help feed the Mexican Costa Azul LNG facility.
- The pipeline expansion of Transwestern would consist of 516 miles of 42-inch pipeline and nine compressor stations in Arizona, New Mexico, and Texas.
- Design capacity of the pipeline is 1.5 Bcf/d and estimated in service date by 4Q 2029.
- The project is supported by long-term agreements from invenstment-grade customers and the compay plans to launch an open season later this quarter.
Tallgrass Proposes new Permian to Rockies Express Pipeline
- Market Impact: The new proposed pipeline could serve a varity of demand centers depending on where it would connect with Rockies Express (REX). Rockies gas production has been on the decline and is expected to continue into the future. Tallgrass has an extensive pipeline system in the Rockies that can reach the West Coast and demand centers in the Midwest.
- Tallgrass anounced anchor shipper precedent agreementsfor a new pipeline that will move gas from the Permian Basin to the Rockies Express Pipeline and other points of delivery.
- The company said there are sufficient agreements to financially justify construction of the project with an in-service date in late 2028.
WhiteWater Announces FID on Traverse Pipeline
- Market Impact: This pipe is important for moving gas toward the Houston and eventually, toward LNG in Louisiana. However, it does not add extra egress for those exposed to Waha gas prices.
- WhiteWater, MPLX LP, and Enbridge Inc., have partnered with an affiliate of Targa to move forward with the construction of the Traverse Pipeline.
- The Traverse Pipline will be a bi-directional, 160 mile, 36-inch pipeline along the Gulf Coast between Agua Dulce in South Texas and the Katy area.
- The pipeline will transport up to 1.75 Bcf/d and will be sourced from multiple locations such as Whistler, Blackcomb, and Matterhorn Express Pipeline.
Expansion of NGL and Natural Gas Takeaway From MPLX with Gulf Coast Projects
- Market Impact: Added gas processing and pipeline expansions in the Permian will mean more gas reaching the Gulf to feed LNG growth through the end of the decade.
- MPLX reported a significant uptick in its natural gas and NGL services in late 2024
- New infrastructure includes the Gulf Coast fractionation complex, which will feature two 150 MBbl/d facilities, anticipated to come online by 2028 and 2029
- The company is also working with ONEOK to build a 400 MBbl/d LPG export terminal and pipeline that is expected to come online in 2028
- MPLX also mentioned that the Blackcomb and Rio Bravo Pipelines will enhance natural gas transport from the Permian to the Gulf Coast. The company is also boosting natural gas processing facilities, including the Secretariat processing plant in the Permian. The new facilities are expected to add 1.4 Bcf/d of processing capacity by late 2025.
Blackfin Pipeline gets approval to build lateral connection to LNG
- Market Impact: A connection between Blackfin and CP Express means Permian gas could flow down Matterhorn—another WhiteWater pipeline—to Blackfin, then to CP Express and CP2 LNG. This, along with Kinder Morgan’s FID-approved Trident Pipeline, would help debottleneck the Katy and Houston area and route gas around Houston to the Beaumont/Port Arthur area.
- The Blackfin Pipeline, owned by WhiteWater Midstream, was approved by the RRC on Jan. 28 for the addition of two laterals, including a 0.55-mile, 48-inch CP Express Delivery Lateral.
- The CP Express Pipeline will deliver gas from far southeast Texas to Venture Global's proposed CP2 LNG project in Cameron Parish, Louisiana.
- The other approved lateral, called the Matterfin Lateral, is 0.2 miles long and would likely link to the Matterhorn Express Pipeline, allowing West Texas gas to connect more easily to Louisiana LNG.
- Blackfin started construction on the mainline in October 2024, according to RRC data.
Energy Transfer reaches FID on 2.2 Bcf/d Permian pipeline
- Market impact: The addition of the Hugh Brinson pipeline in the winter of '26/'27 will likely add to the region's pipeline takeaway capacity overbuild. The Waha forward curve in 2027 reflects this reality.
- Previously known as the Warrior Pipeline. The pipe has been renamed to Hugh Brinson.
- The project is a 400 miles of 42" pipeline with an initial capacity of 1.5 Bcf/d.
- Phase II will boost pipeline capacity to 2.2 Bcf/d, depending on demand.

Don’t stop here. See how other regions are performing right now:
Haynesville — Appalachian — Rockies — Midcon
Want this in your inbox?
AEGIS market analysts publish research across crude, natural gas, NGLs, refined products, metals, and rates.
Subscribe to research