Crude prices moved sharply lower this week amid renewed US-Iran diplomatic efforts and a shifting political backdrop following the US midterm elections. The election results added to expectations that the administration could face greater pressure to pursue a negotiated settlement, while President Trump said the US has no immediate plans for further strikes. Iran also submitted a new nuclear proposal to Washington through Qatar, although Tehran has said negotiations will not proceed until the US addresses its seven demands. Together, the developments encouraged traders to remove some geopolitical risk premium, although the path toward a durable agreement remains highly uncertain.
The physical market has also begun to show clearer signs of loosening. JPMorgan estimates the global oil market moved into a 1.1 MMBbl/d surplus in September before widening to roughly 1.4 MMBbl/d in October as Middle Eastern exports recovered, production increased elsewhere and demand weakened. S&P Global Commodities estimates Middle Eastern crude exports averaged 15.2 MMBbl/d in October, equivalent to roughly 80% of prewar levels. Saudi Aramco also cut the December OSP for Arab Light sold into Asia by $2/Bbl to a $7/Bbl discount to the Oman/Dubai average, reinforcing signs that the physical crude market is becoming less tight.
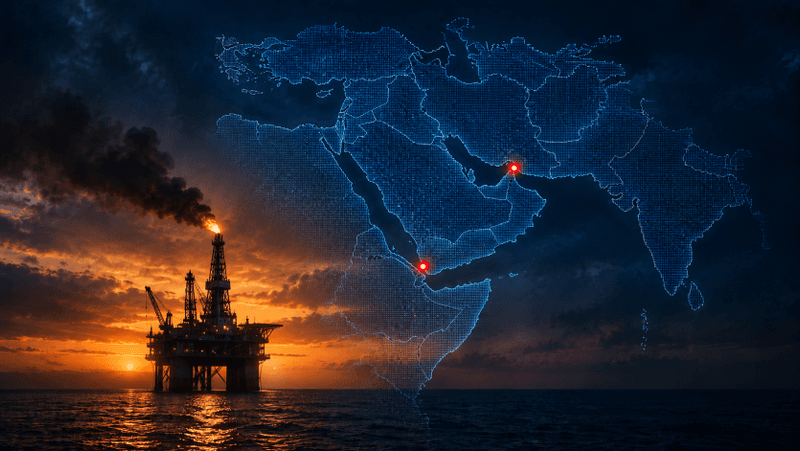
Still, the security situation around Hormuz remains unresolved. UKMTO has reported at least five incidents involving vessels in the Persian Gulf and Strait of Hormuz since Sunday, including a tanker struck north of Qatar. Shipping through the strait remains disrupted and no durable US-Iran agreement has been reached, leaving the market vulnerable to a rapid rebuilding of geopolitical risk premium if talks stall or attacks intensify.
Global supply buffers also remain considerably thinner than before the conflict. ADNOC estimates nearly 1 billion barrels of crude have been drawn from inventories since disruptions around Hormuz began, leaving less flexibility to absorb another material supply interruption.
AEGIS maintains a bullish view on Bal 26 WTI. The near-term fundamental picture has become less supportive as Middle Eastern exports recover and the global balance moves back into surplus. However, the risk of renewed military escalation remains high as US-Iran negotiations continue without a breakthrough and shipping through the Strait of Hormuz remains disrupted. With inventories materially depleted, another deterioration in regional production or exports could quickly tighten the balance again. We therefore continue to see near-term risks tilted to the upside, while sustained diplomatic progress and continued export normalization remain the primary downside risks.
We remain neutral on Cal 27. The underlying 2027 supply-and-demand balance remains considerably more bearish if Middle Eastern production and trade normalize. The EIA projects global inventories to build by roughly 4.9 MMBbl/d next year as regional production recovers and alternative export capacity expands. The election result and improving physical supply arguably strengthen that normalization case, but continued uncertainty around Hormuz and the durability of any US-Iran agreement keeps us neutral relative to the current curve.
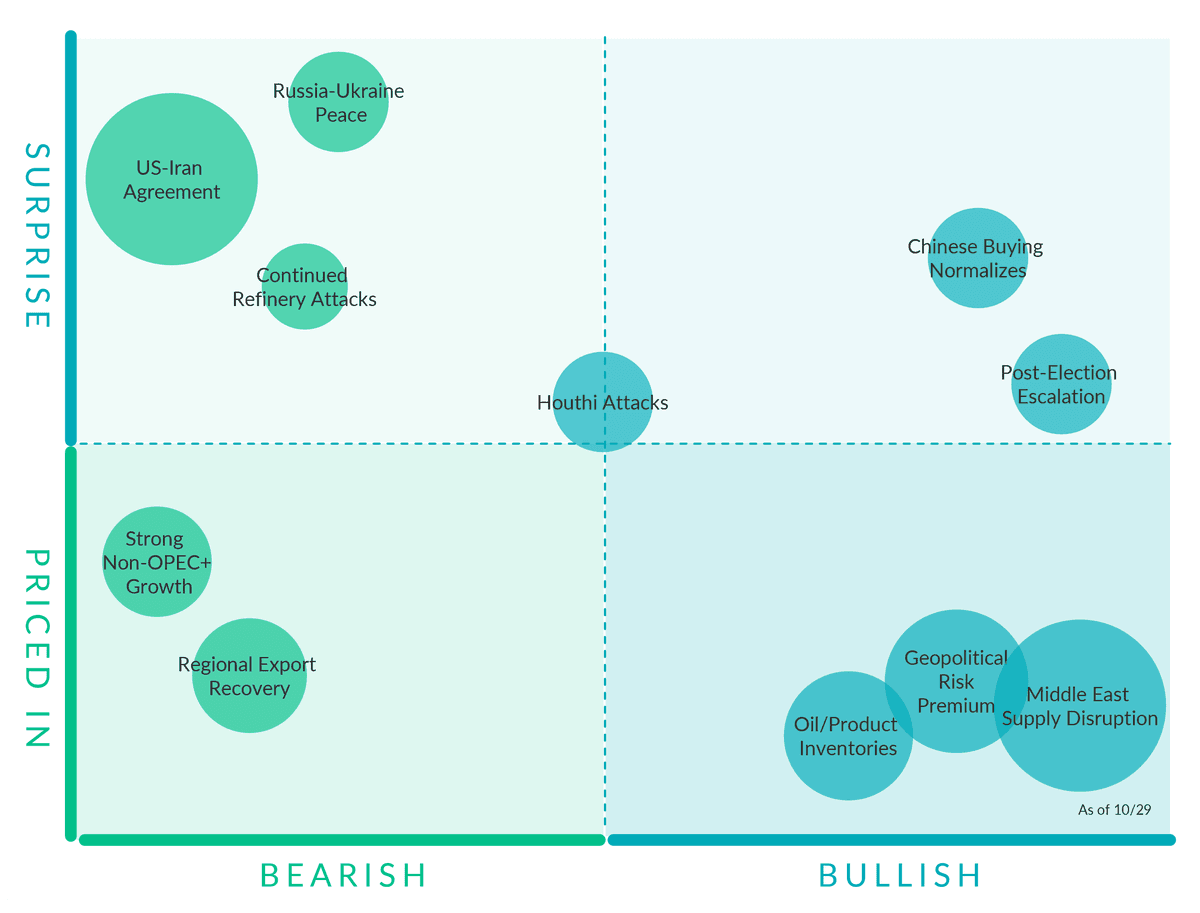
Crude Oil Factors
US-Iran Agreement (Bearish, Surprise) - Qatar-mediated negotiations continue, but Washington and Tehran have not reached an agreement. A settlement that improves shipping security and eases restrictions on Iranian exports could remove additional geopolitical premium and accelerate the recovery in available supply.
Russia-Ukraine Peace (Bearish, Surprise) - US-mediated talks between Russia and Ukraine are scheduled for November 10–11 in Abu Dhabi, although the parties remain far apart. An agreement that reduces attacks on energy infrastructure and leads to broader sanctions relief could improve the reliability of Russian crude and product exports, adding downward pressure to prices.
Continued Refinery Attacks (Bearish, Priced In) - Renewed Ukrainian attacks on Russian refineries threaten to reverse the recovery in processing seen during late October. Reuters reported an attack on Yaroslavl and indications of another at Ryazan this week. Extended outages could reduce crude demand and leave more barrels available for export while tightening diesel supply.
Strong Non-OPEC+ Growth (Bearish, Priced In) - Rising production from Brazil, Guyana and Argentina continues to increase available supply. Alongside recovering Middle Eastern exports and weaker demand, this contributed to JPMorgan’s estimated global surplus of 1.4 MMBbl/d in October. Continued growth would increase competition for buyers and weigh on longer-dated crude prices.
Regional Export Recovery (Bearish, Priced In) - Gulf exports remain substantially above wartime lows, easing physical shortages, but the recovery remains uneven. Preliminary Vortexa estimates put October crude, condensate and refined-product exports excluding LPG at 17.1 MMBbl/d, down from 18.9 MMBbl/d in September. Further normalization would pressure prices, although shipping risks continue to constrain the recovery.
Houthi Attacks (Neutral, Surprise) - Saudi Arabia issued alerts around the Yanbu export hub on November 5 as Houthi attacks continued. The crude-price impact depends on the infrastructure affected. Refinery outages can reduce crude demand, while damage to pipelines, processing facilities or export terminals could restrict supply. Confirmed damage and outage duration will determine the net effect.
Chinese Buying Normalizes (Bullish, Surprise) - Chinese crude imports rose to 9.03 MMBbl/d in September, while October arrivals were projected to exceed 10 MMBbl/d, according to Reuters’ October 21 analysis. Sustained purchasing would support physical differentials, although higher imports can reflect inventory replenishment as well as stronger consumption.
Inventories Reach Minimums (Bullish, Surprise) - The IEA’s October report placed on-land oil inventories at their lowest levels since at least 2016. Further supply disruptions could push usable stocks toward operational minimums in exposed markets, amplifying increases in prompt prices and time spreads. Recovering supply reduces this risk, but rebuilding depleted buffers will take time.
Post-Election Escalation (Bullish, Surprise) - The midterm result has changed the political backdrop, but Trump retains substantial authority over foreign policy and military operations. Renewed strikes on Iranian energy infrastructure, or retaliation against Gulf production and export facilities, could reverse recent supply gains and extend disruptions into 2027.
Geopolitical Risk Premium (Bullish, Priced In) - The post-election selloff removed a substantial portion of crude’s geopolitical premium, while renewed tanker incidents helped prices rebound. Unresolved security risks continue to support prices, although the remaining premium is vulnerable to credible progress toward dependable shipping and a durable agreement.
Oil/Product Inventories (Bullish, Priced In) - The IEA estimates observed global oil inventories were 509 MMBbl lower at end-September than at end-February. US commercial crude inventories fell to 412.5 MMBbl in the week ended October 16, 3% below the five-year average, while distillates remained 9% below average. Reduced inventories leave less protection against disruptions and support near-term scarcity premiums.
Middle East Supply Disruption (Bullish, Surprise) - The Washington Institute recorded 28 confirmed and reported attacks in the Strait of Hormuz and surrounding waterways during October as of October 23, according to Reuters. A sustained reduction in flows or damage to ship-to-ship transfer locations could reverse recent supply gains and tighten prompt balances, creating further upside risk.