Skip to content
AEGIS Hedging
Market Insights

Crude Oil

War Extends Through April, Driving Further Shifts in April STEO Crude Outlook

Narciso Cano2 min read

The latest Short-Term Energy Outlook (STEO) highlights a crude market that has rapidly shifted from surplus to disruption-driven tightness following the ef...

The latest Short-Term Energy Outlook (STEO) highlights a crude market that has rapidly shifted from surplus to disruption-driven tightness following the effective closure of the Strait of Hormuz. With the EIA now assuming the conflict persists through the end of April, the agency has made significant revisions to supply, demand, inventories, and price expectations. What was previously a well-supplied market is now defined by large-scale production shut-ins, accelerating inventory draws, and elevated price risk.

Note: The April STEO was released prior to the announced ceasefire agreement and therefore does not reflect any potential near-term de-escalation in the conflict.

War Extends Through April, Driving Further Shifts in April STEO Crude Outlook: chart 1
Source: AEGIS Hedging

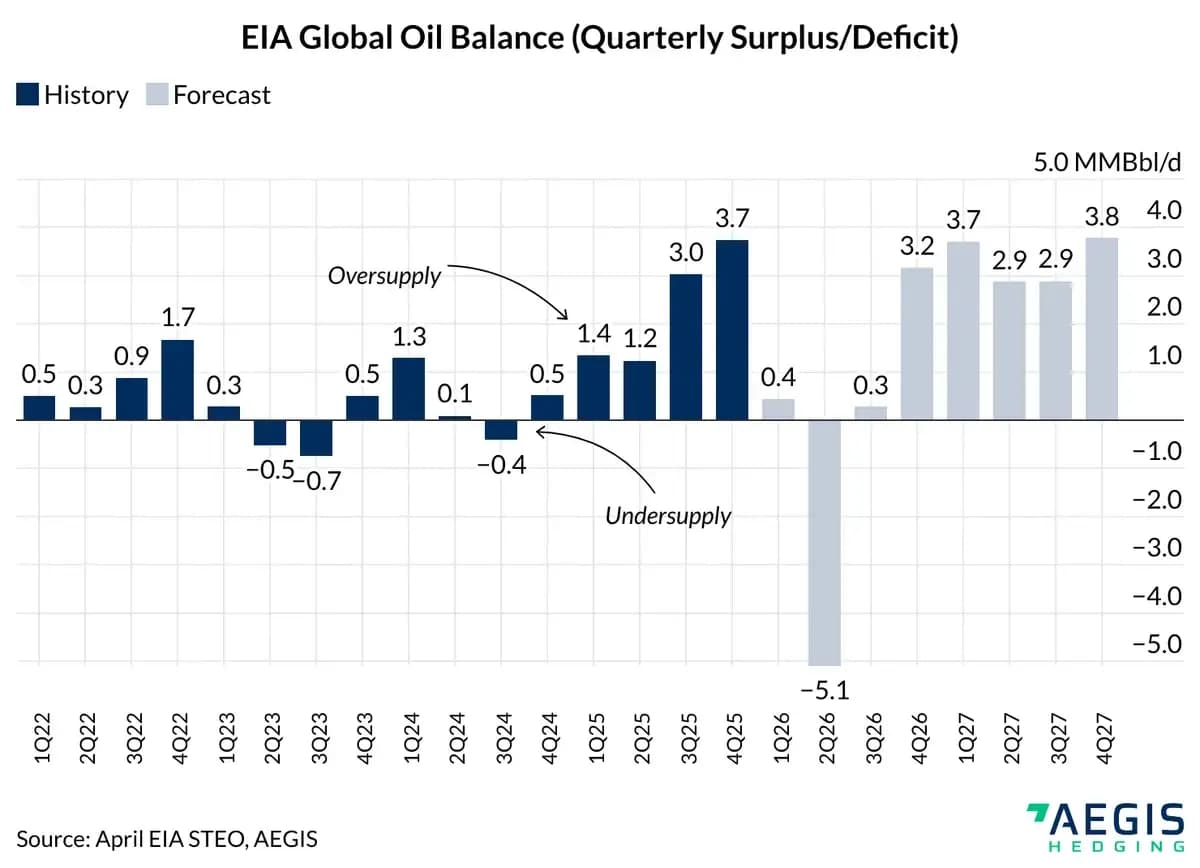
The most critical change lies in supply. The EIA now estimates that crude production shut-ins averaged 7.5 MMbbl/d in March and will peak at roughly 9.1 MMbbl/d in April. These disruptions are materially tightening global balances, with the agency projecting a 5.1 MMbbl/d inventory draw in the second quarter alone. The scale of these losses reflects both the physical constraints on tanker traffic and the growing impact of infrastructure risks across the region. While strategic stock releases from the U.S. and coordinated efforts from the International Energy Agency provide some offset, they are not sufficient to fully replace disrupted flows.

War Extends Through April, Driving Further Shifts in April STEO Crude Outlook: chart 2
Source: AEGIS Hedging

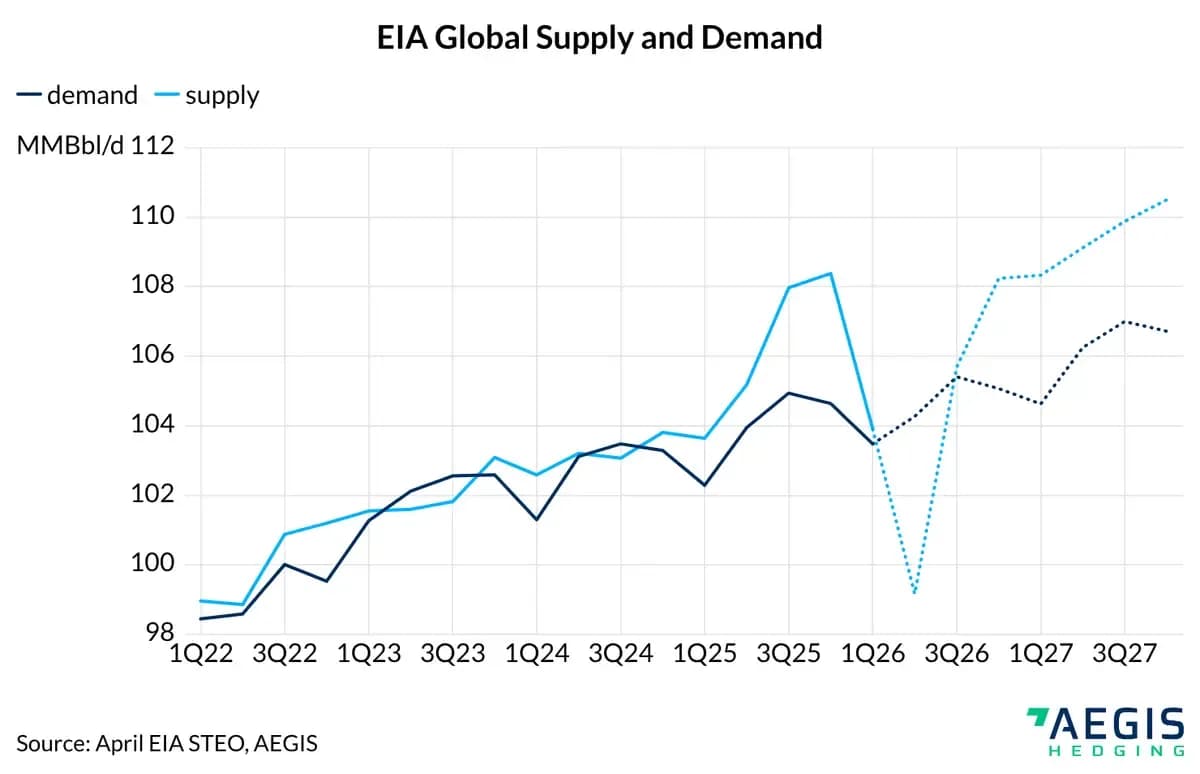
Demand assumptions have also been revised lower, though not enough to offset the supply shock. The EIA now expects global demand growth of 0.6 million b/d in 2026, down from 1.2 million b/d previously, as fuel shortages and policy measures, particularly in Asia, reduce consumption. Despite this downward revision, the market remains undersupplied in the near term due to the magnitude of production losses.

War Extends Through April, Driving Further Shifts in April STEO Crude Outlook: chart 3
Source: AEGIS Hedging

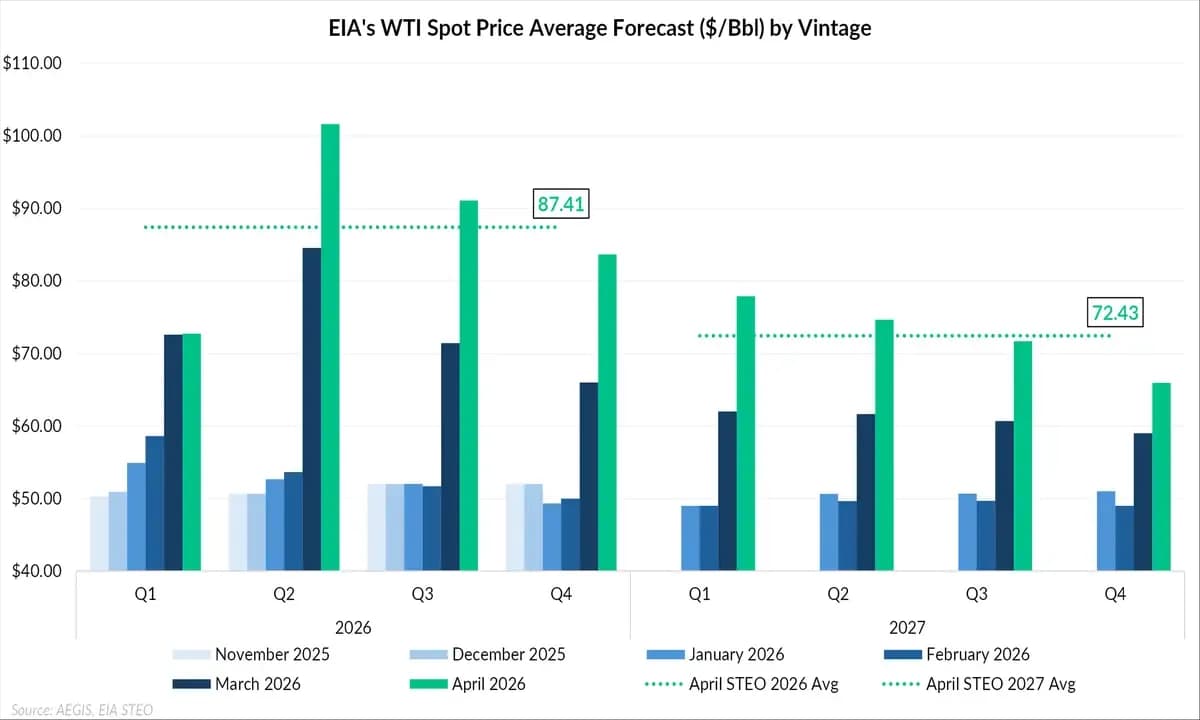
These dynamics are most clearly reflected in inventories and prices. Global inventories, which were previously expected to build, are now drawing sharply as disrupted supply outweighs weaker demand. This shift has pushed near-term prices materially higher, with WTI now expected to average $87.41/bbl in 2026, $13.80 higher than last month’s forecast, and remaining supported by ongoing supply risk and limited spare capacity. The EIA also notes that even after flows resume, a backlog in tanker routes and continued geopolitical risk will sustain a premium in crude prices for an extended period.

In sum, the April STEO reinforces a more severe version of the same two-phase narrative. The market has moved from expected oversupply to acute near-term tightness, driven by sustained disruptions through April. While the EIA still assumes flows will gradually normalize and balances will loosen over time, the path back to surplus is now delayed, and the near-term crude market remains significantly tighter than previously anticipated.

Want this in your inbox?

AEGIS market analysts publish research across crude, natural gas, NGLs, refined products, metals, and rates.

Stay Ahead

Get market insights delivered to your inbox — for free.

We use a few essential cookies to make our site work, including one that counts how many reports you have opened. Analytics cookies are used only with your permission, and you can change your mind at any time. Learn more about cookies in our privacy policy.