The start of March has seen a surge in trading activity as oil producers moved aggressively to hedge production following a sharp rally in crude prices. The increase in hedging activity comes after the launch of the US’s Operation Epic Fury, which intensified an already volatile geopolitical environment in the Middle East.
As an oil and gas hedging advisor, we recorded a record volume of crude hedged on Monday, March 2, and crude hedging activity on March 3 was also heavy, just shy of Monday’s record.
In a recent analysis of call-skew signals in the crude options market, we highlighted how traders were increasingly paying up for upside protection as geopolitical risks intensified. As headlines escalated and military operations began, that premium expanded rapidly, driving crude prices higher.
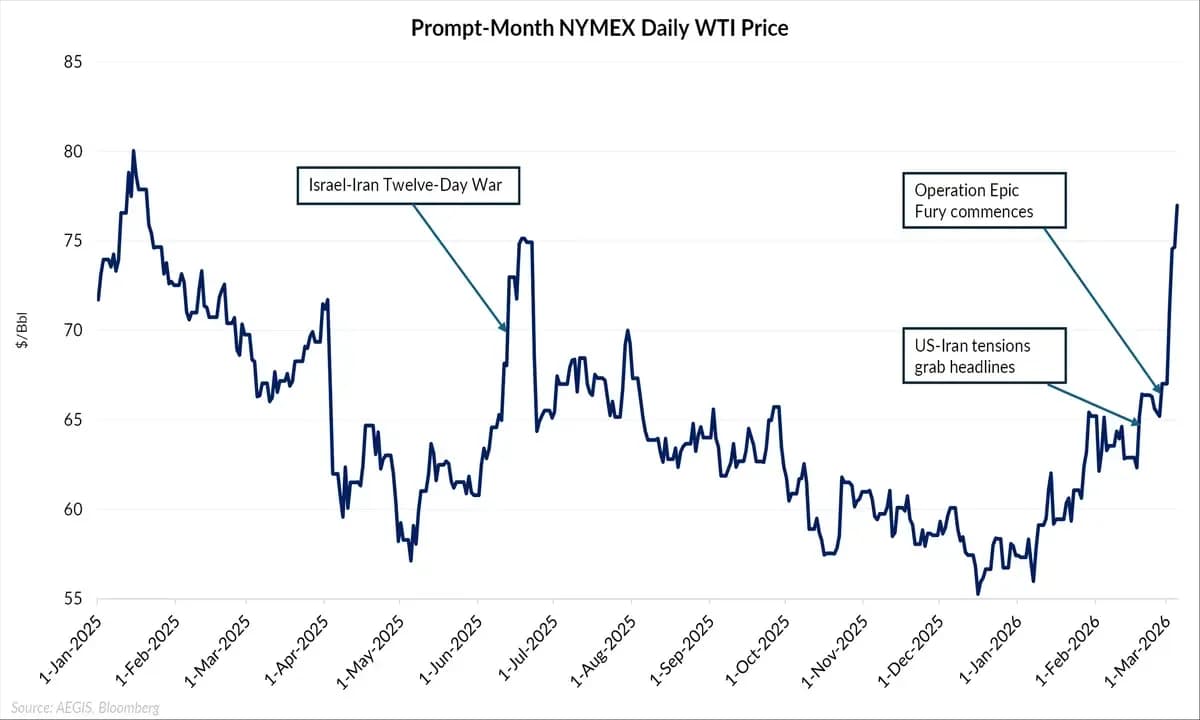
As shown in the chart above, WTI prices began climbing in February as US–Iran tensions increasingly dominated headlines before accelerating sharply following the launch of US and Israeli military operations, pushing prompt WTI toward the mid-$70s. The rapid repricing offered producers a materially improved price environment compared with levels available only weeks earlier, helping explain the surge in trading activity seen at the start of March.
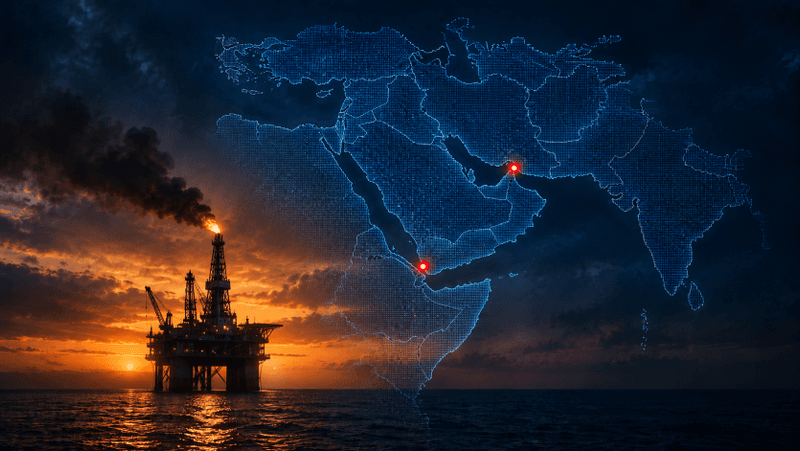
The central risk driving the rally is the Strait of Hormuz, one of the most important chokepoints in global energy markets. Roughly 20% of global oil supply transits the waterway, meaning any disruption to flows could have significant implications for global supply balances. Analysts note that the duration of any disruption through Hormuz will likely determine the trajectory of oil prices. In a prolonged blockage scenario, several institutions see prices ballooning into the $100–$120/Bbl range.
Storage constraints across Gulf producers represent another key risk if exports through the Strait of Hormuz remain restricted. JP Morgan estimates that the region holds just under 400 MMBbls of total available storage, equivalent to roughly 25 days of production before tanks begin to fill. Once that capacity is exhausted, producers would be forced to shut in output. Early signs of this pressure are already emerging, with Iraq beginning to curtail production, highlighting how geopolitical tensions are now translating into tangible supply losses.
Chronology of Events Behind the Recent Crude Price Rally
- February 15–20 — Pre-conflict positioning: Iranian and Gulf producers increase exports and reduce storage levels ahead of a potential confrontation, while war-risk insurance premiums for tankers transiting the Strait of Hormuz begin rising sharply.
- February 28 — Operation Epic Fury begins: More than 100 US aircraft launch coordinated strikes on Iranian targets, marking the formal start of the war between the US, Israel, and Iran.
- February 28–March 1 — Shipping disruptions escalate: Major oil traders and shipping companies begin suspending crude and LNG shipments through Hormuz as vessels anchor outside the strait and insurers reassess war-risk coverage.
- March 1 — Iranian retaliation spreads regionally: Iran launches missile and drone strikes targeting Gulf energy infrastructure and regional military bases, including attacks on ports and tanker traffic.
- March 2 — Iran threatens ships transiting Hormuz: Iranian officials declare that vessels attempting to pass through the strait could be attacked, effectively halting tanker traffic through the key global energy chokepoint.
- March 3–5 — Shipping crisis deepens: Tankers become stranded on both sides of the Strait as insurers and operators suspend transits, disrupting global oil trade, leading to production shut-ins and prompting refiners to seek alternative supplies.
Ultimately, the sustainability of the recent price rally will hinge on how long disruptions to shipping through the Strait of Hormuz persist. If transit through the waterway normalizes quickly, the geopolitical premium embedded in crude prices could unwind just as rapidly, allowing prices to fall back toward levels implied by relatively loose supply-demand fundamentals.
In the meantime, the recent surge has provided producers with an opportunity to hedge volumes at significantly improved price levels, helping explain the wave of trading activity seen in the opening days of March.