Crude Oil
Risk Premium Unwinds as Hormuz Reopens but Uncertainty Still Looms
Crude prices moved sharply lower this week after Iran signaled a reopening of the Strait of Hormuz, easing immediate supply fears and triggering a rapid unwind of geopolitical risk premium. The WTI prompt-month contract settled Friday at $83.85/bbl, down $12.72 week over week. While headlines pointed to de-escalation through ceasefire developments and official statements, underlying physical constraints remain unresolved.
Earlier in the week, the market was positioned for a deepening supply shock after the US implemented its own blockade of the Strait of Hormuz following failed negotiations in Islamabad. The breakdown in talks removed a near-term diplomatic off-ramp and raised the risk of additional supply losses, particularly with Iran’s ~2 MMbbl/d of exports at stake.
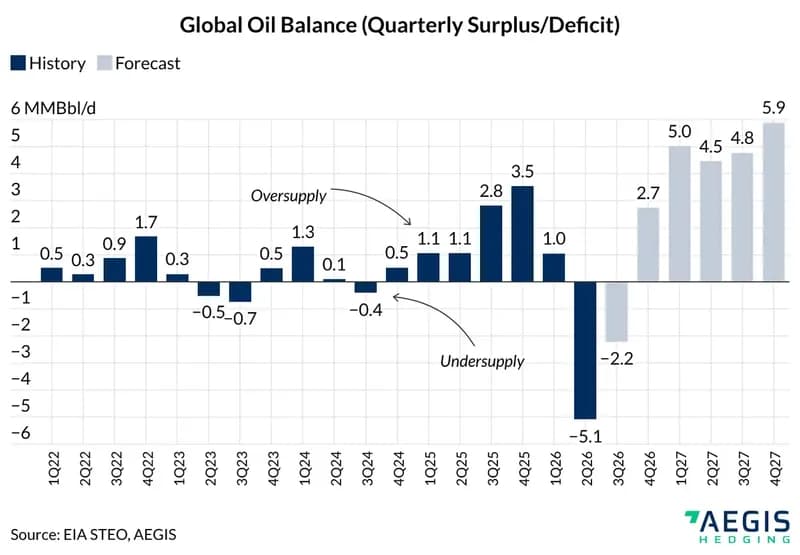
At the same time, major agency reports highlighted a growing divergence in demand expectations. OPEC continues to project relatively strong demand growth of ~1.4 MMbbl/d in 2026. The EIA has taken a more cautious stance, revising growth down to ~0.6 MMbbl/d amid weaker consumption in Asia tied to higher prices and disruption effects. The IEA remains the most bearish, now forecasting a contraction in global oil demand in 2026 of ~80 Mbbl/d, a reversal from prior expectations of ~650 Mbbl/d growth. This represents a roughly 730 Mbbl/d downward revision month over month. Reinforcing the softer macro backdrop, the IMF also lowered its global growth outlook, citing conflict-driven uncertainty, with GDP now expected to expand 3.1% under a short disruption scenario and as low as ~2.0% in a more severe escalation case.
Despite the apparent de-escalation, operational clarity in the Strait remains limited. Iranian Foreign Minister Abbas Araghchi indicated that commercial vessel traffic would resume under the ceasefire framework. However, conflicting reports from Iranian media suggest that transit restrictions may still apply to vessels linked to “hostile” countries, with requirements for coordination with Iranian authorities and the potential for renewed closure if US restrictions persist. As seen throughout the conflict, market pricing continues to react more quickly to headlines than to actual changes in physical flows.
Looking ahead, the situation remains highly fluid. The ceasefire falls short of a formal resolution, leaving uncertainty elevated as both sides hold firm on key issues including nuclear policy and potential tolling mechanisms in the Strait of Hormuz. With flows through the strait still unclear, the physical balance remains constrained despite the sharp pullback in prices. As a result, AEGIS maintains a neutral view, recognizing that while risk premium has softened, underlying fundamentals remain tight.
Natural Gas
Natural gas prices languish amid mild weather
The May Henry Hub contract traded 3c lower this week to settle at $2.68/MMBtu, extending losses. The Winter ‘26/’27 seasonal strip lost another 5c to settle at $3.95/MMBtu and Summer ’27 fell 2c to finish the week at $3.72/MMBtu. Weak weather driven demand continues to weigh on prices and a cold front this weekend will do little to materially lift gas demand.
Lower-48 temperatures are forecast to fall slightly below the ten-year average over the next two weeks, in a shift from the particularly mild temperatures seen over the past few weeks. However, this will only give a slight boost to gas demand and storage injections will continue. The mild temperatures have resulted in Lower-48 gas inventories climbing to a +108 Bcf surplus to the five-year average. This week the EIA reported a 59 Bcf injection, which was the third consecutive report to show an expanding surplus.
Pipeline maintenance has weighed on production with volumes falling to 107.8 Bcf/d this week, according to data from S&P. This represents a drop of about 1 Bcf/d from the prior weeks average. Shoulder season maintenance may keep production limited, helping to support the supply-demand balance, but once maintenance concludes, output should return to prior levels. However, the limited demand and pipe maintenance has impacted basis, especially in west Texas. Day-ahead Waha basis prices fell to a new all-time low this week of -$9.50/MMBtu. The forward curve shows only limited improvement this summer, with the remainder of the Summer ’26 strip trading at -$4.63/MMBtu. Stress on Waha basis should continue until more pipeline capacity becomes available later this year heading into winter.