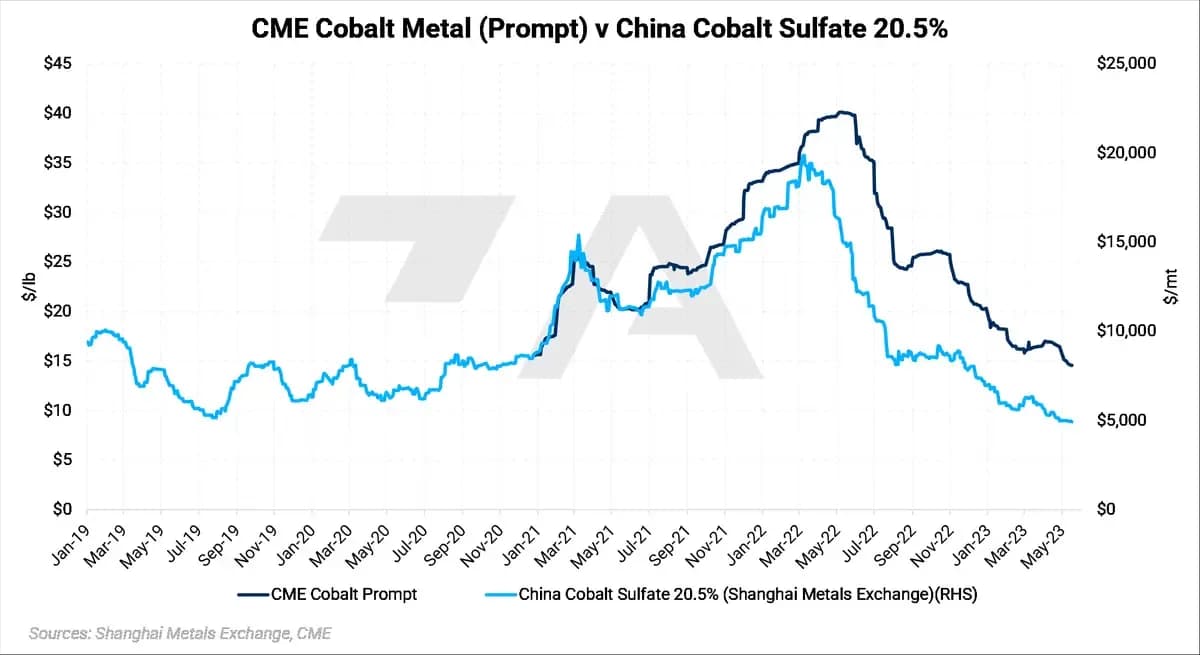
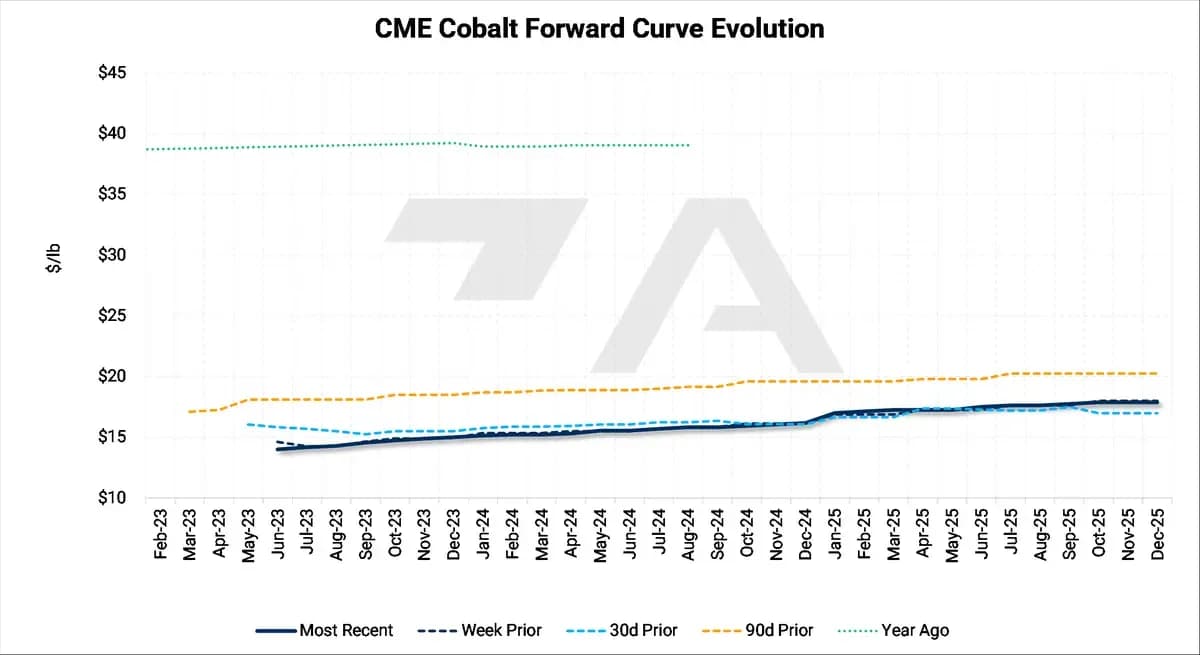
Ample global supplies of cobalt have pressured both CME cobalt prices and Chinese Cobalt Sulfate prices. Prices for both have pushed to pandemic-era lows. Specifically for CME Cobalt metal, which only started trading in late December 2020, prices are at an all-time low. Even though the CME Cobalt market is in contango, end-users can lock in prices nearly 60% lower compared to this time last year.
China is the world's largest cobalt end-user, so its prices and demand can have global implications. Cobalt sulfate is the closest cobalt product to the battery industry, so its prices can give a relatively good assessment of Chinese supply and demand. As we can see, prices for both metal and sulfate have dropped substantially since mid-2022. |
|---|
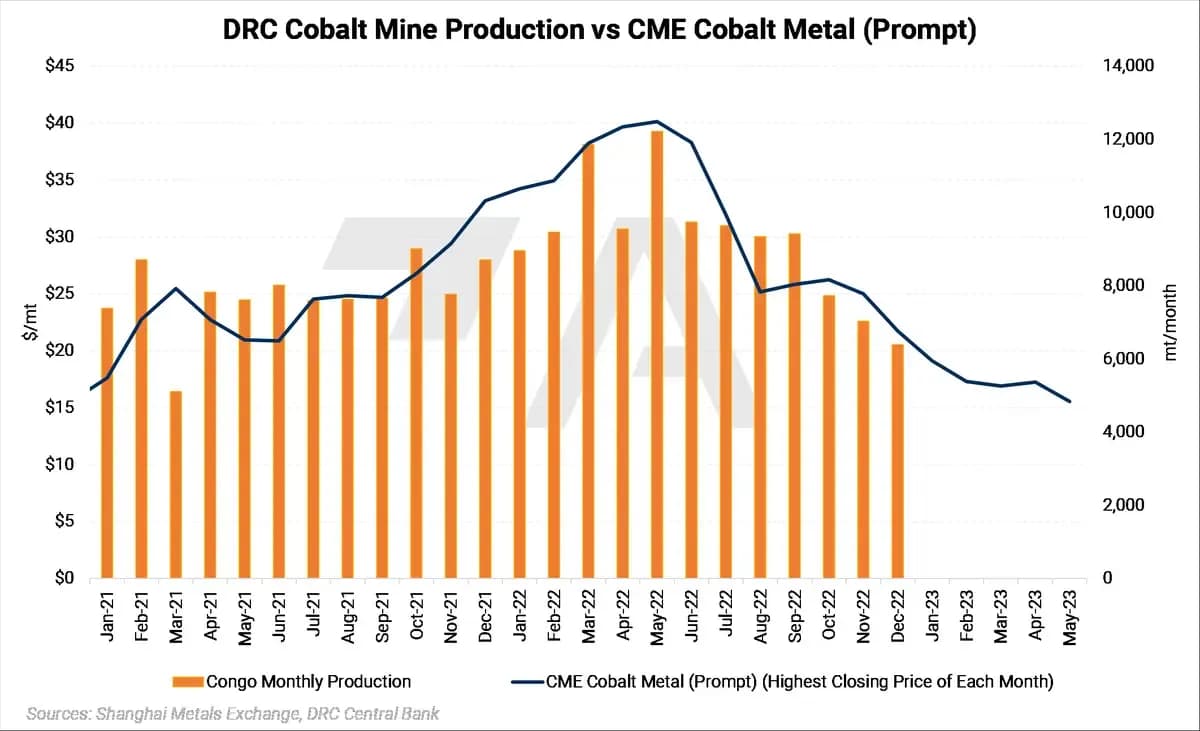
According to Ag Metal Miner, mine production continues at a blistering pace, despite ample supply and subpar demand. The Democratic Republic of the Congo, which is the world’s largest cobalt miner, produced a record 111,000 mt last year, according to data from the DRC Central Bank. Analysts recently interviewed by Ag Metal Miner believe that the DRC will produce 180,000 mt this year. (Please note that if these estimates for 2023 production prove accurate, the DRC would mine on average 15,000 mt per month, which is slightly outside the scale of the chart below. Since at least 2012, monthly production has never exceeded 15,000 mt.) |
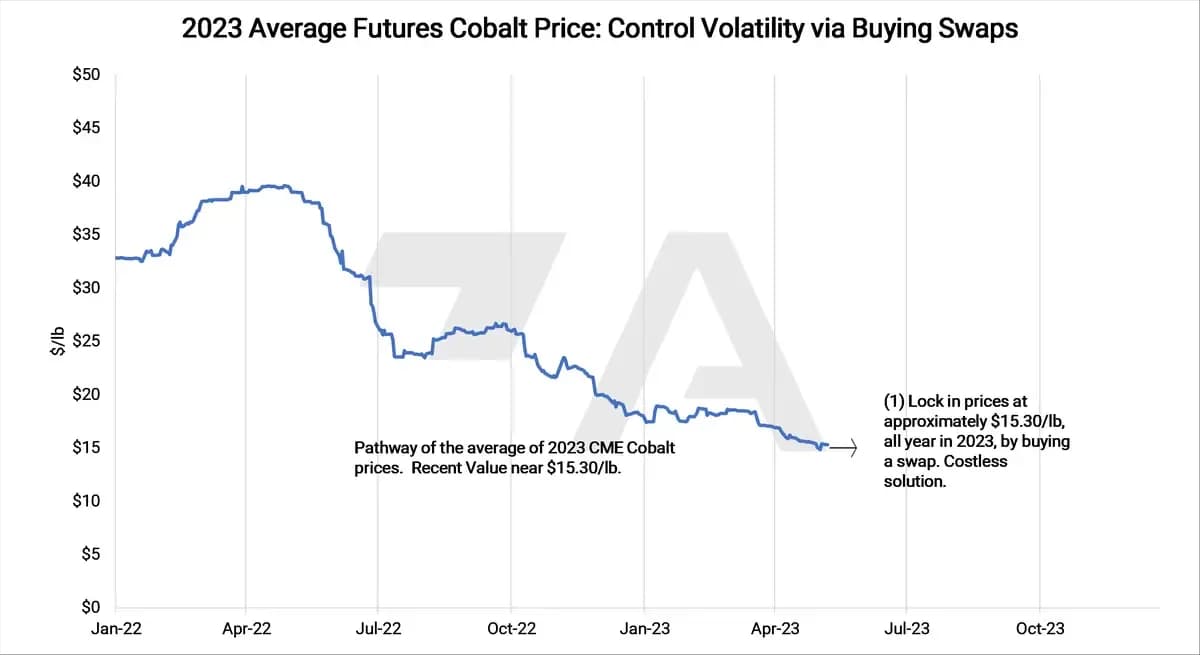
As we suggested above, cobalt end-users can use the recent price drop to hedge their long-term needs. CME cobalt’s futures forward curve is in a steep contango, but end-users still lock in prices that are nearly 60% lower compared to this time last year. |
There is no options market for CME Cobalt, so the only hedging strategies are via futures or swaps. Please contact us for specific strategies that fit your operations. |